
InvestGame contributed to this report, with deal and investment data compiled by their team.
All figures are as of June 30, 2026. LTM (last twelve months) figures are calculated as of the end of Q2.
Market overview
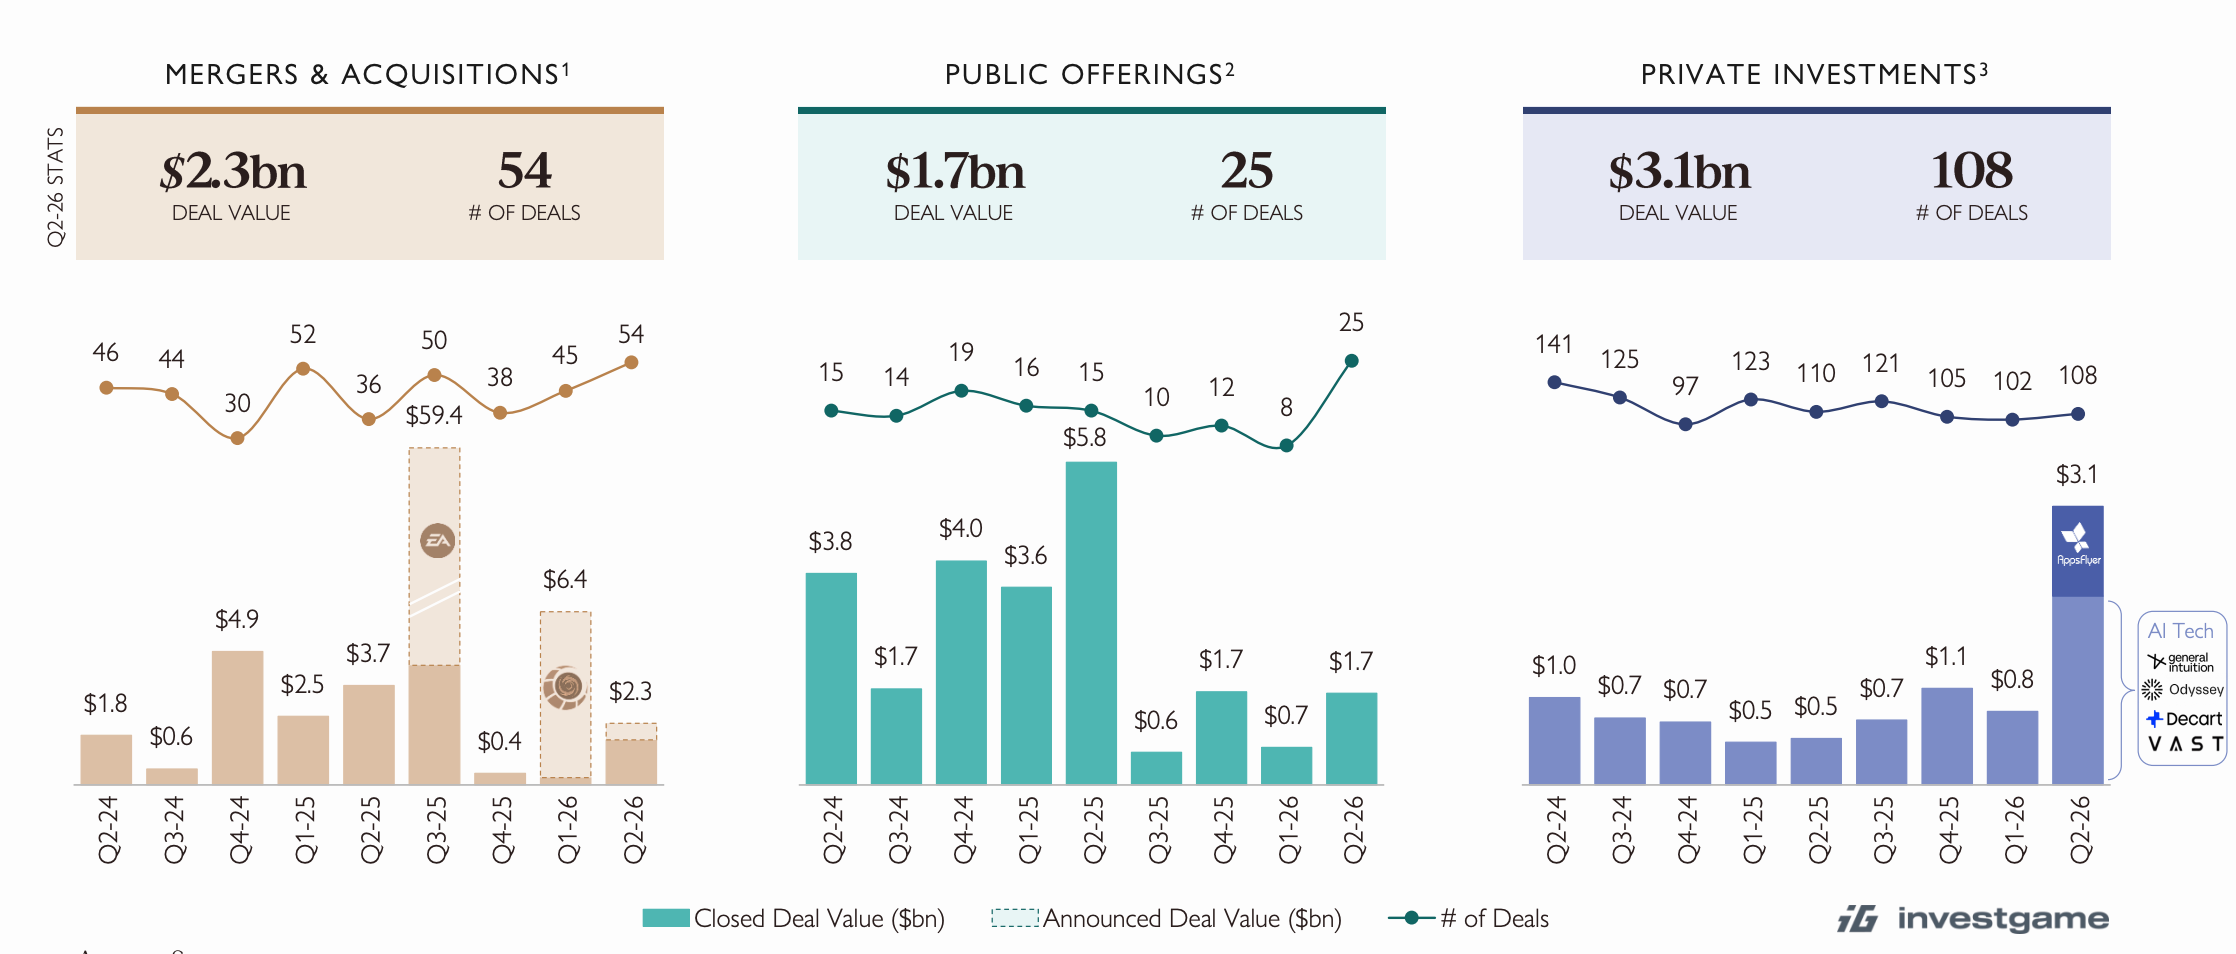
The number of M&A deals in Q2 2026 rose to 54, but their total value declined compared to the previous quarter.
Public market activity in Q2 2026 hit a two-year high. 25 deals closed for a combined $1.7 billion.
Q2 2026 was the biggest quarter for private investment value in two years - $3.1 billion (including the AppsFlyer deal). Most of that capital went into AI tech.
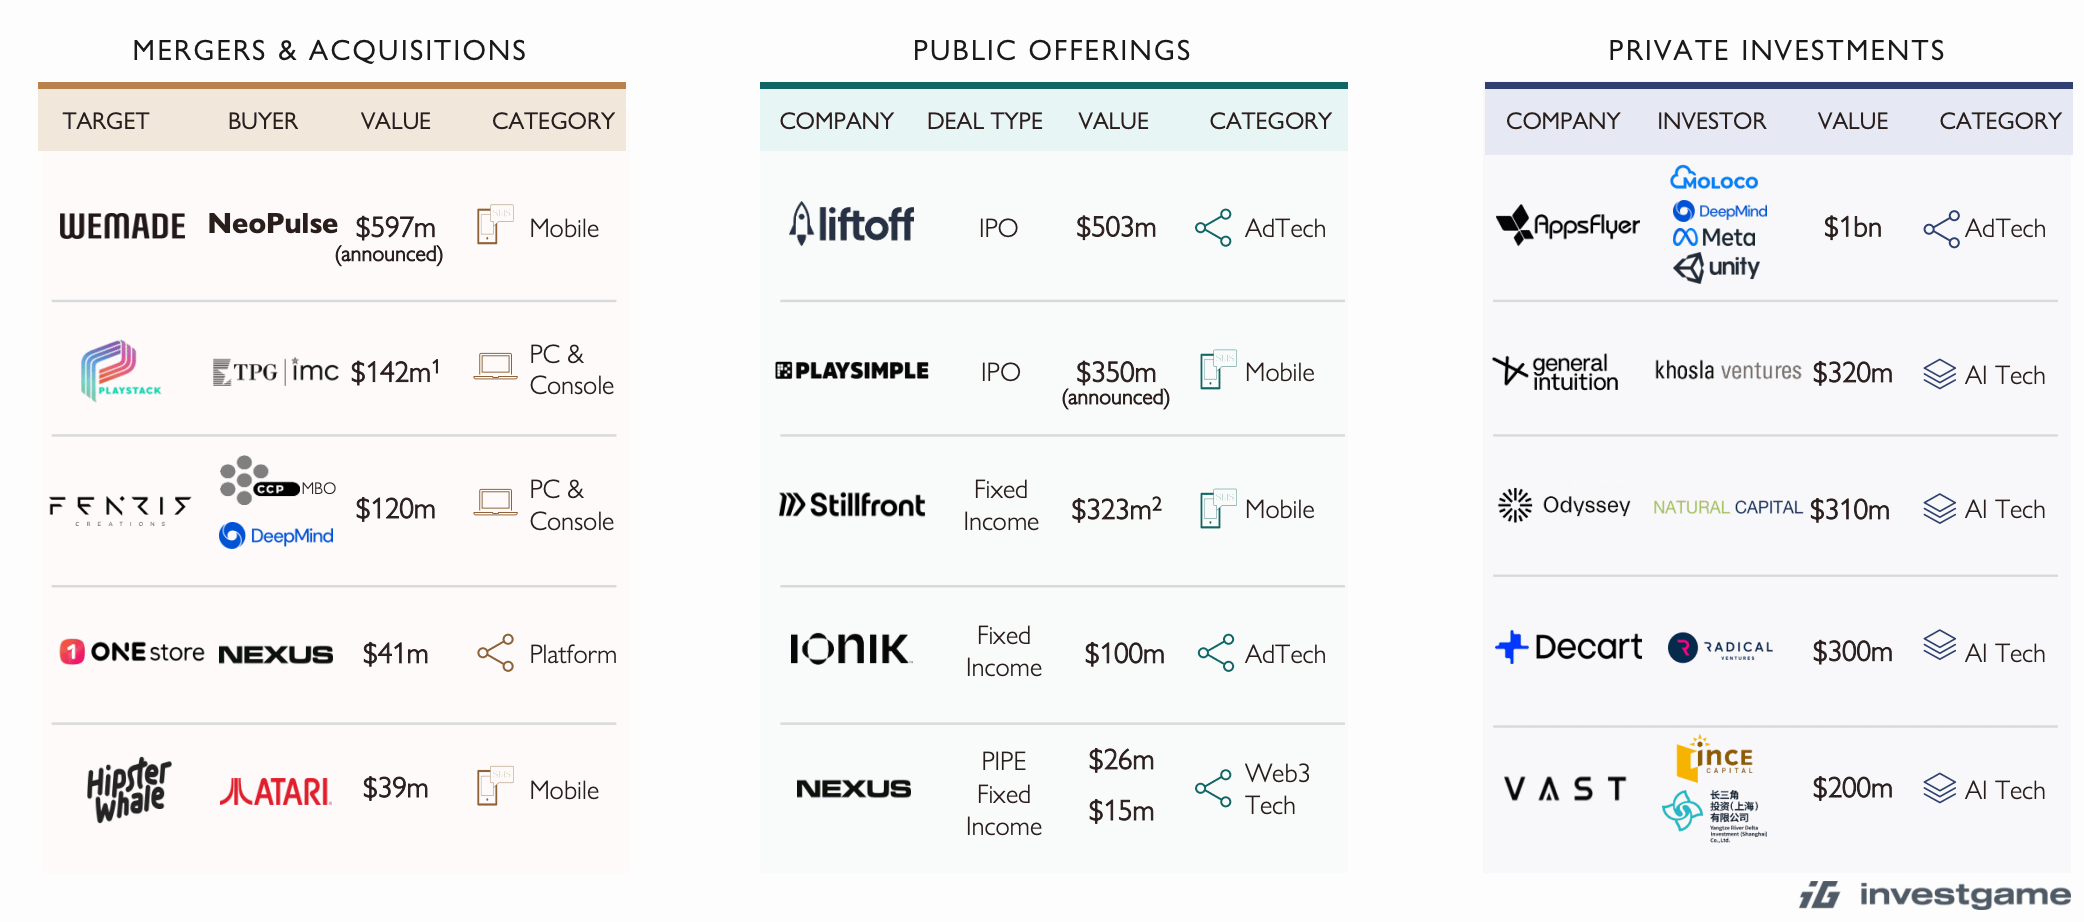
The largest private investment deal of the quarter was the AppsFlyer round, backed by Moloco, DeepMind, Meta, and Unity. The goal is to build an independent MMP given that Adjust is owned by AppLovin.
A word from our sponsor

Still paying for impressions and clicks that never convert? Advertise your PC game with PWN Games! With our CPA model, you only pay when a player installs, engages, or pays. 250+ PC games promoted, 42M+ players acquired, 10 years in the business. Trusted by top PC game publishers worldwide.
Large IPOs are making a comeback for the first time in a while. Liftoff went public (raising $503M at a valuation of nearly $4 billion), and MTG announced plans to list PlaySimple on an Indian stock exchange (aiming to raise $350M).
The largest M&A deal was NeoPulse’s $597 million purchase of the stake held by WeMade’s founder in the company. The deal has been announced but hasn’t closed yet.
Mobile market
Data provided by Sensor Tower.
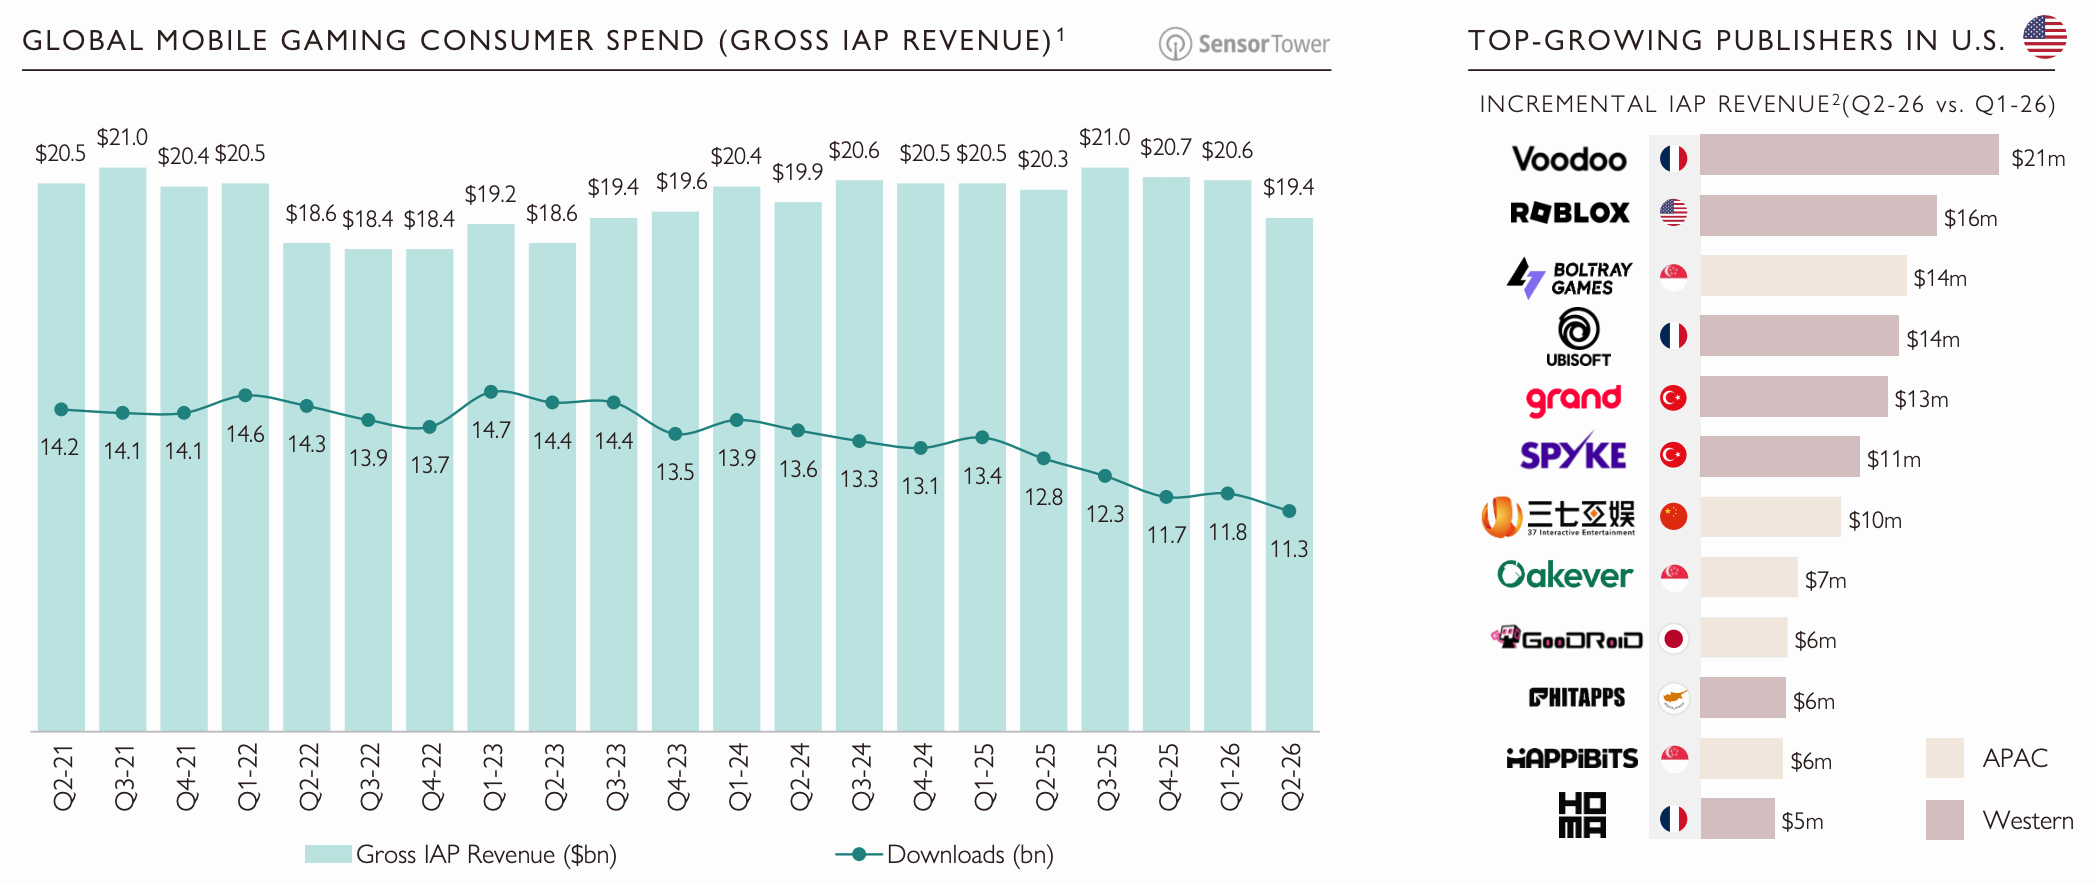
IAP revenue in Q2’26, per Sensor Tower, came in at $19.4 billion - the weakest quarter since Q3’23 and 4% below Q2’25.
❗️But it’s too early to call this a market decline. D2C spend is creating growing blind spots in Sensor Tower’s data.
Installs are at a 5-year low - 11.3 billion. The hoped-for return to growth in Q1’26 didn’t materialize.
Voodoo, Roblox, and Boltray Games led incremental U.S. mobile revenue growth in Q2’26.
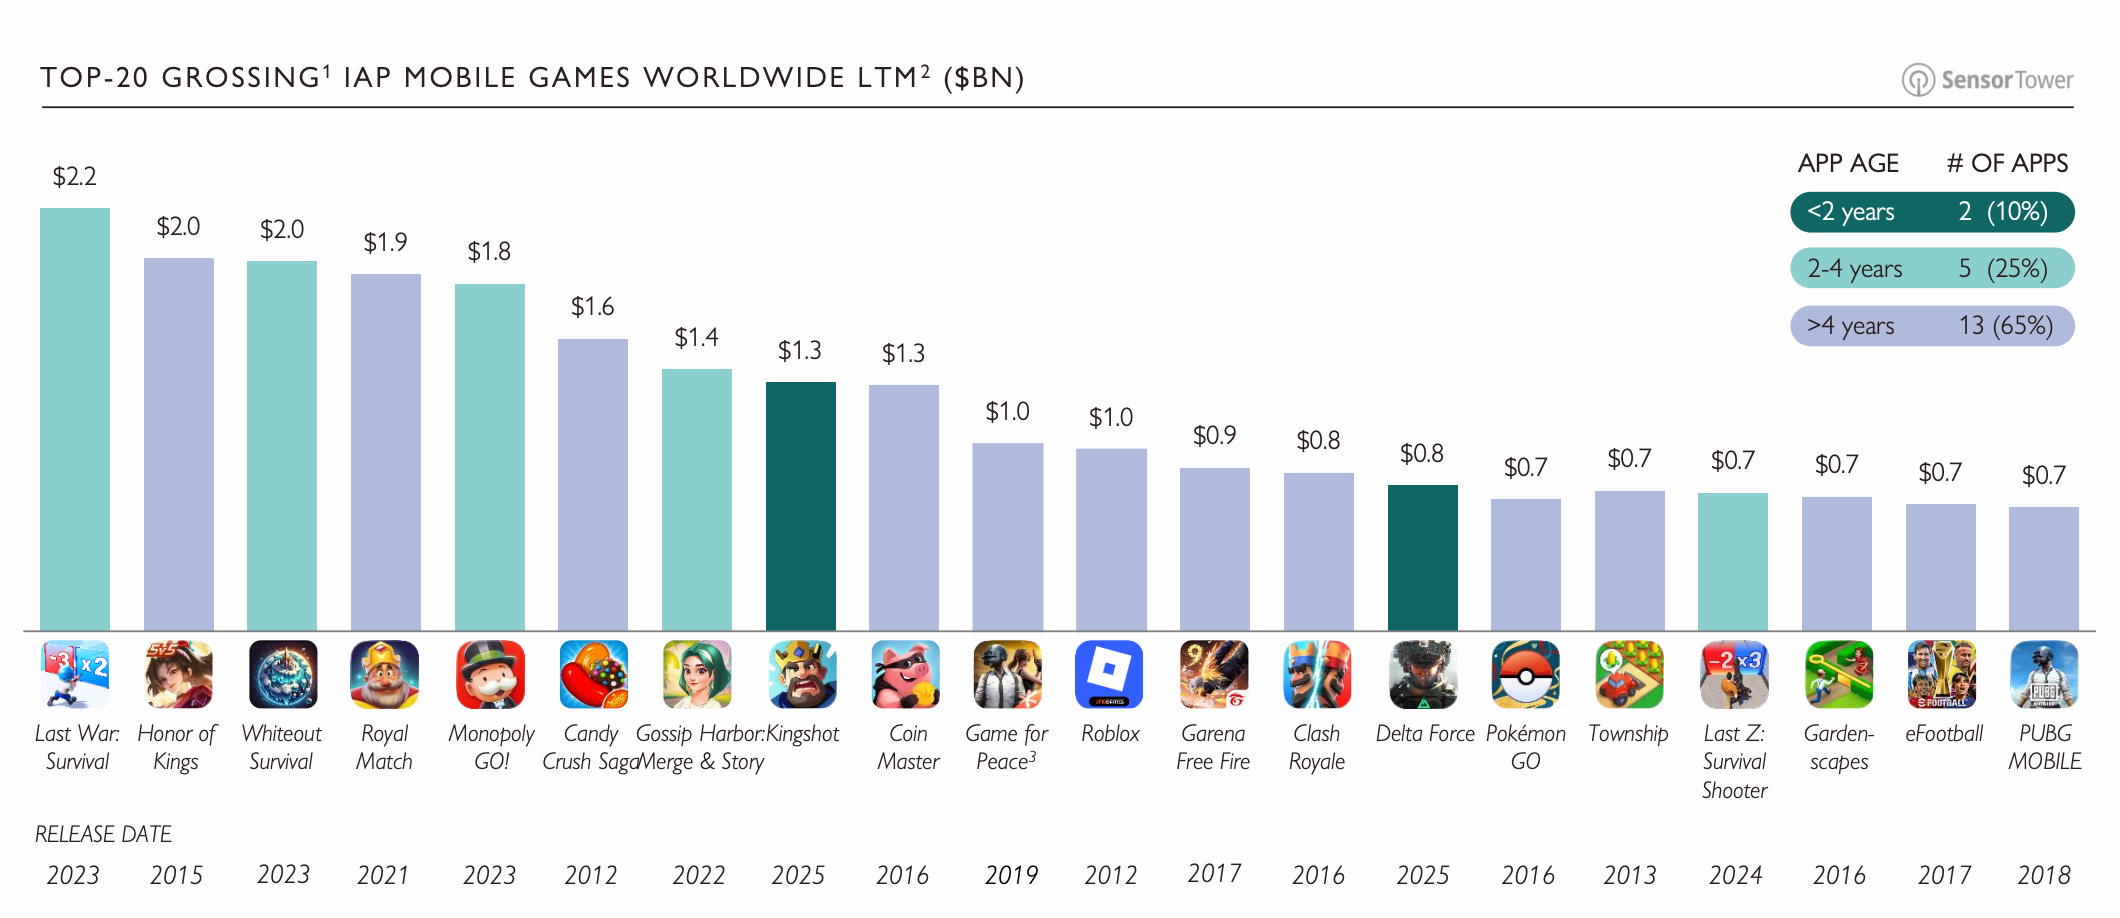
65% of the top-20 games by IAP revenue (LTM) are more than 4 years old - 13 of 20 titles. Games under 2 years old make up just 10% of the list (2 games: Kingshot and Delta Force).
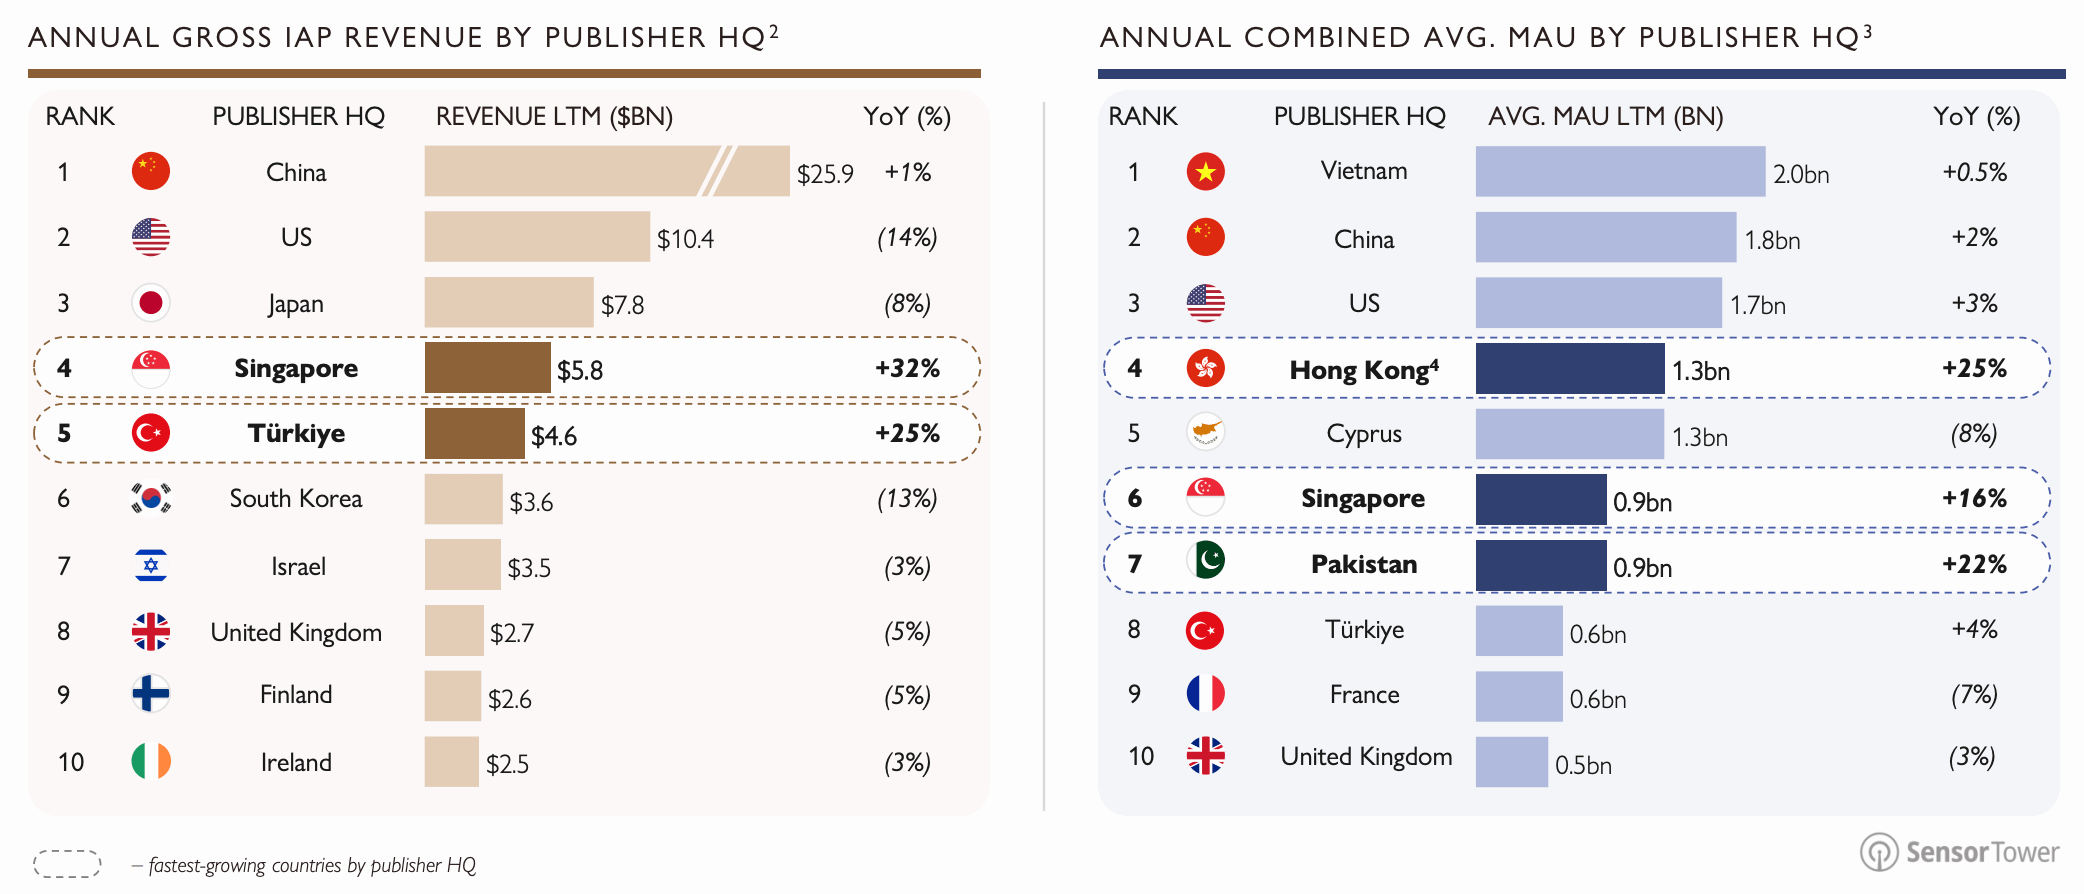
Top countries by IAP revenue over the last 12 months: China - $25.9 billion (+1% YoY), the U.S. - $10.4 billion (-14% YoY), Japan - $7.8 billion (-8% YoY).
The fastest growers are Singapore ($5.8 billion; +32% YoY) and Türkiye ($4.6 billion; +25% YoY).
By average MAU, Vietnam leads (2 billion; +0.5% YoY), followed by China (1.8 billion; +2% YoY) and the U.S. (1.7 billion; +3% YoY).
PC/console market
Data provided by Alinea Analytics.
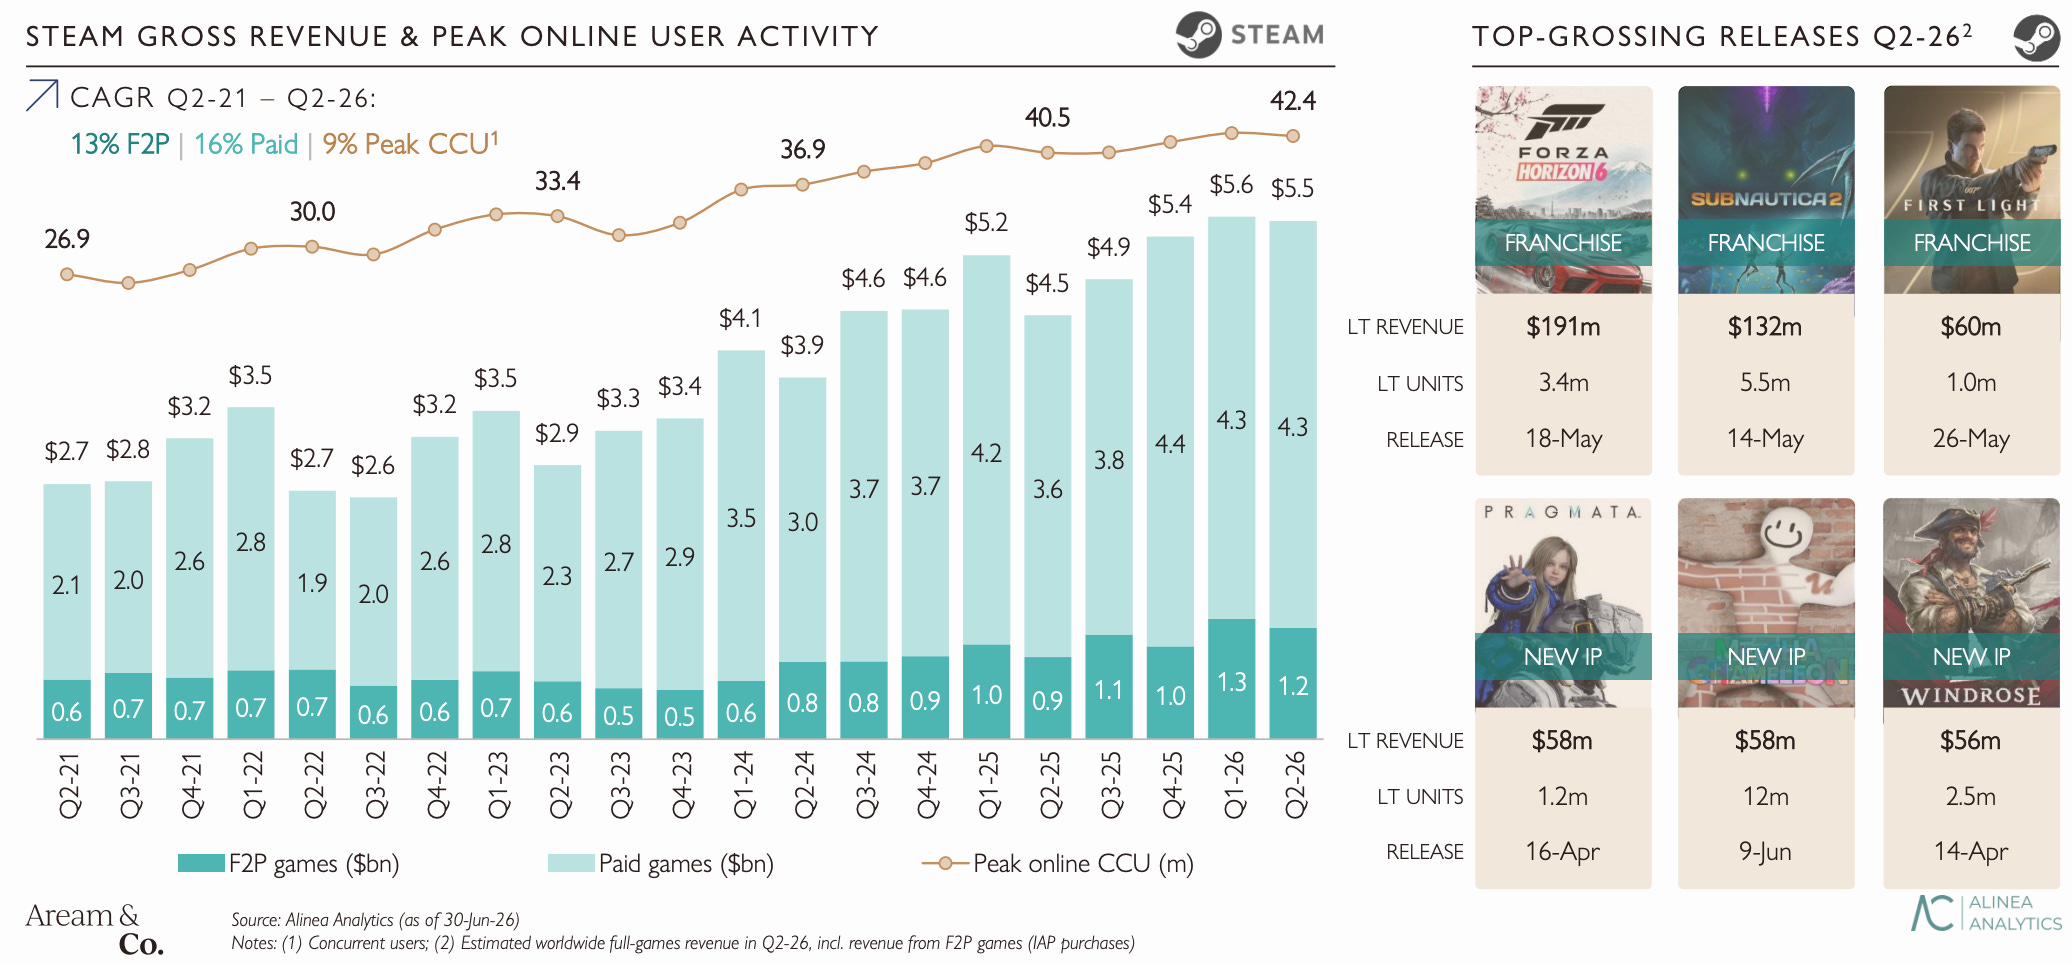
Steam keeps growing at double-digit rates - LTM revenue is up 13% YoY, with peak concurrent users holding near all-time highs despite the usual Q2 seasonal lull.
Steam’s 2021-2026 CAGR: 13% for F2P games, 16% for paid games. CCU metrics grew 9% a year over the same period.
Three of Q2’26’s best launches were new IP: Pragmata ($58 million in revenue), Meccha Chameleon ($58 million), and Windrose ($56 million).
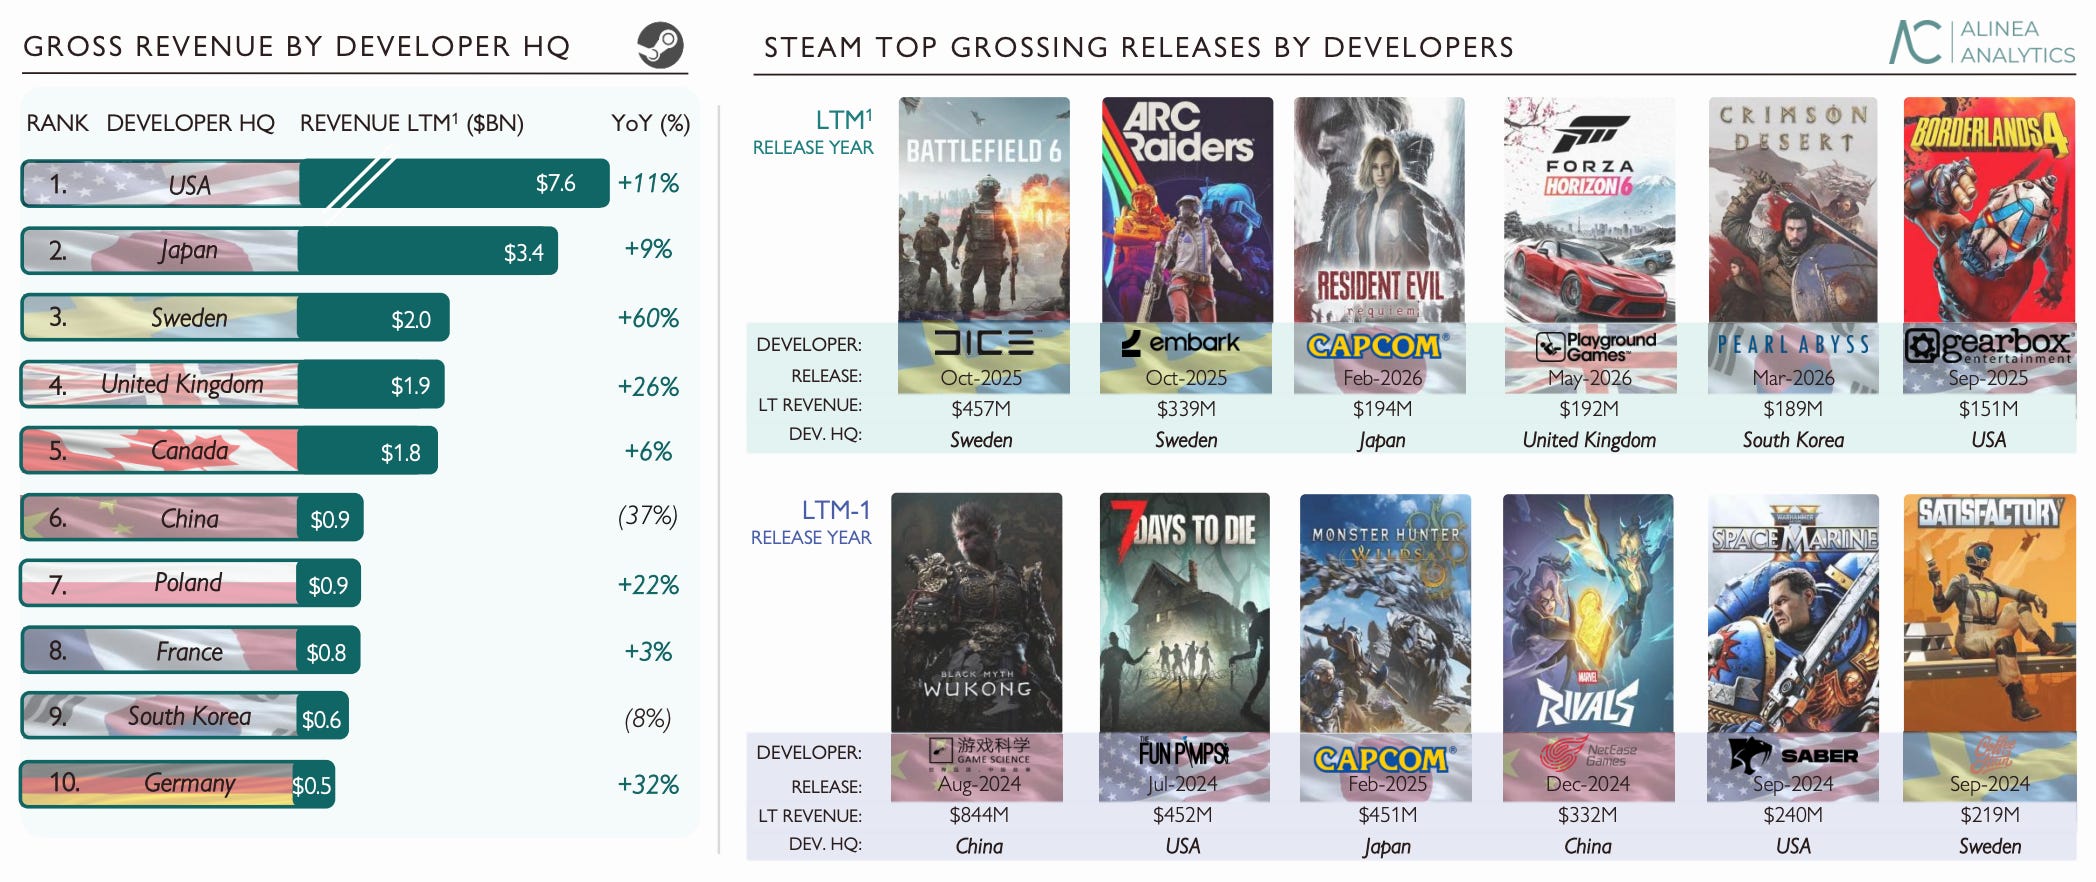
In the country-level revenue ranking for the last 12 months, the U.S. leads with $7.6 billion (+11% YoY), followed by Japan at $3.4 billion (+9% YoY) and Sweden in third at $2 billion (+60% YoY). Western companies dominate the ranking overall.
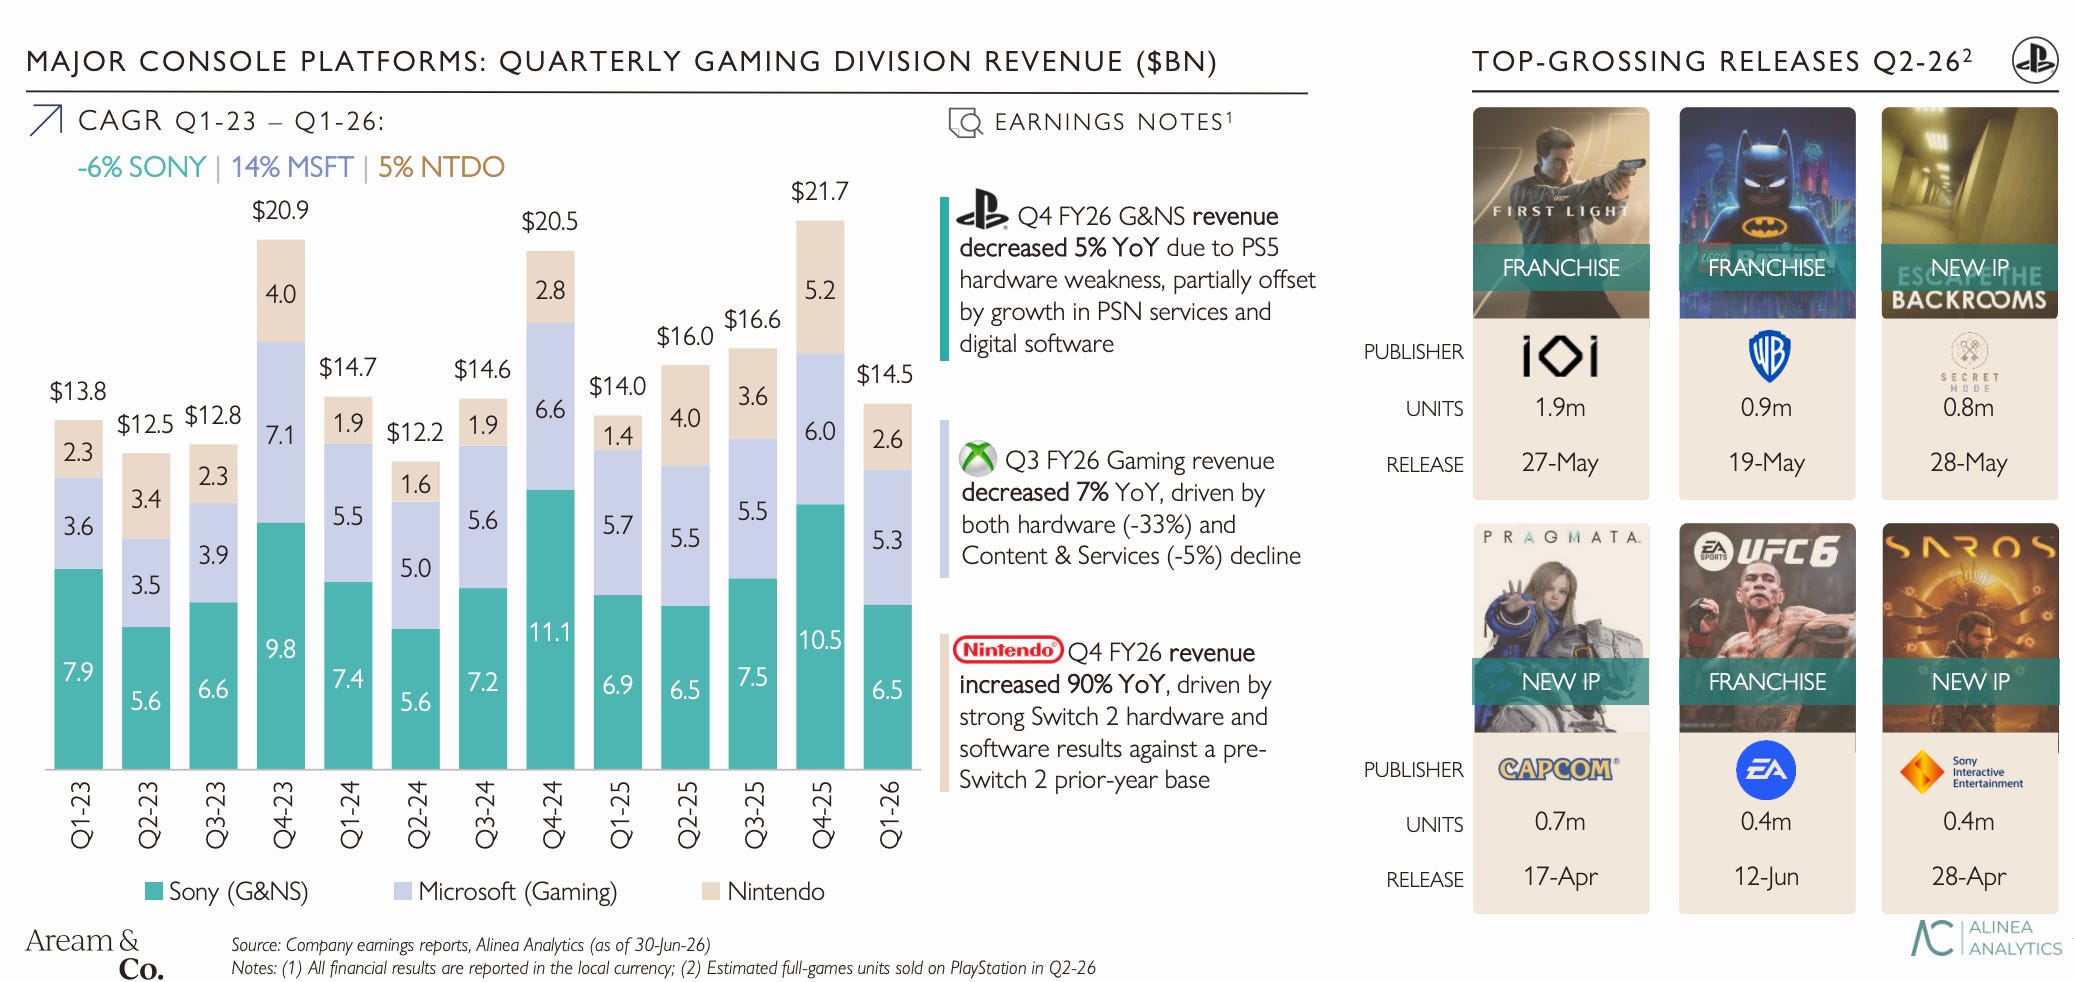
The console market grew 3% YoY, according to the latest earnings reports.
The Nintendo Switch 2 drove Nintendo’s quarterly revenue up 90% YoY.
Sony’s revenue fell 5% (weak console sales, only partly offset by growth in PSN services and digital software). Microsoft’s revenue dropped 7% (hardware sales down 33%, content down 5%).
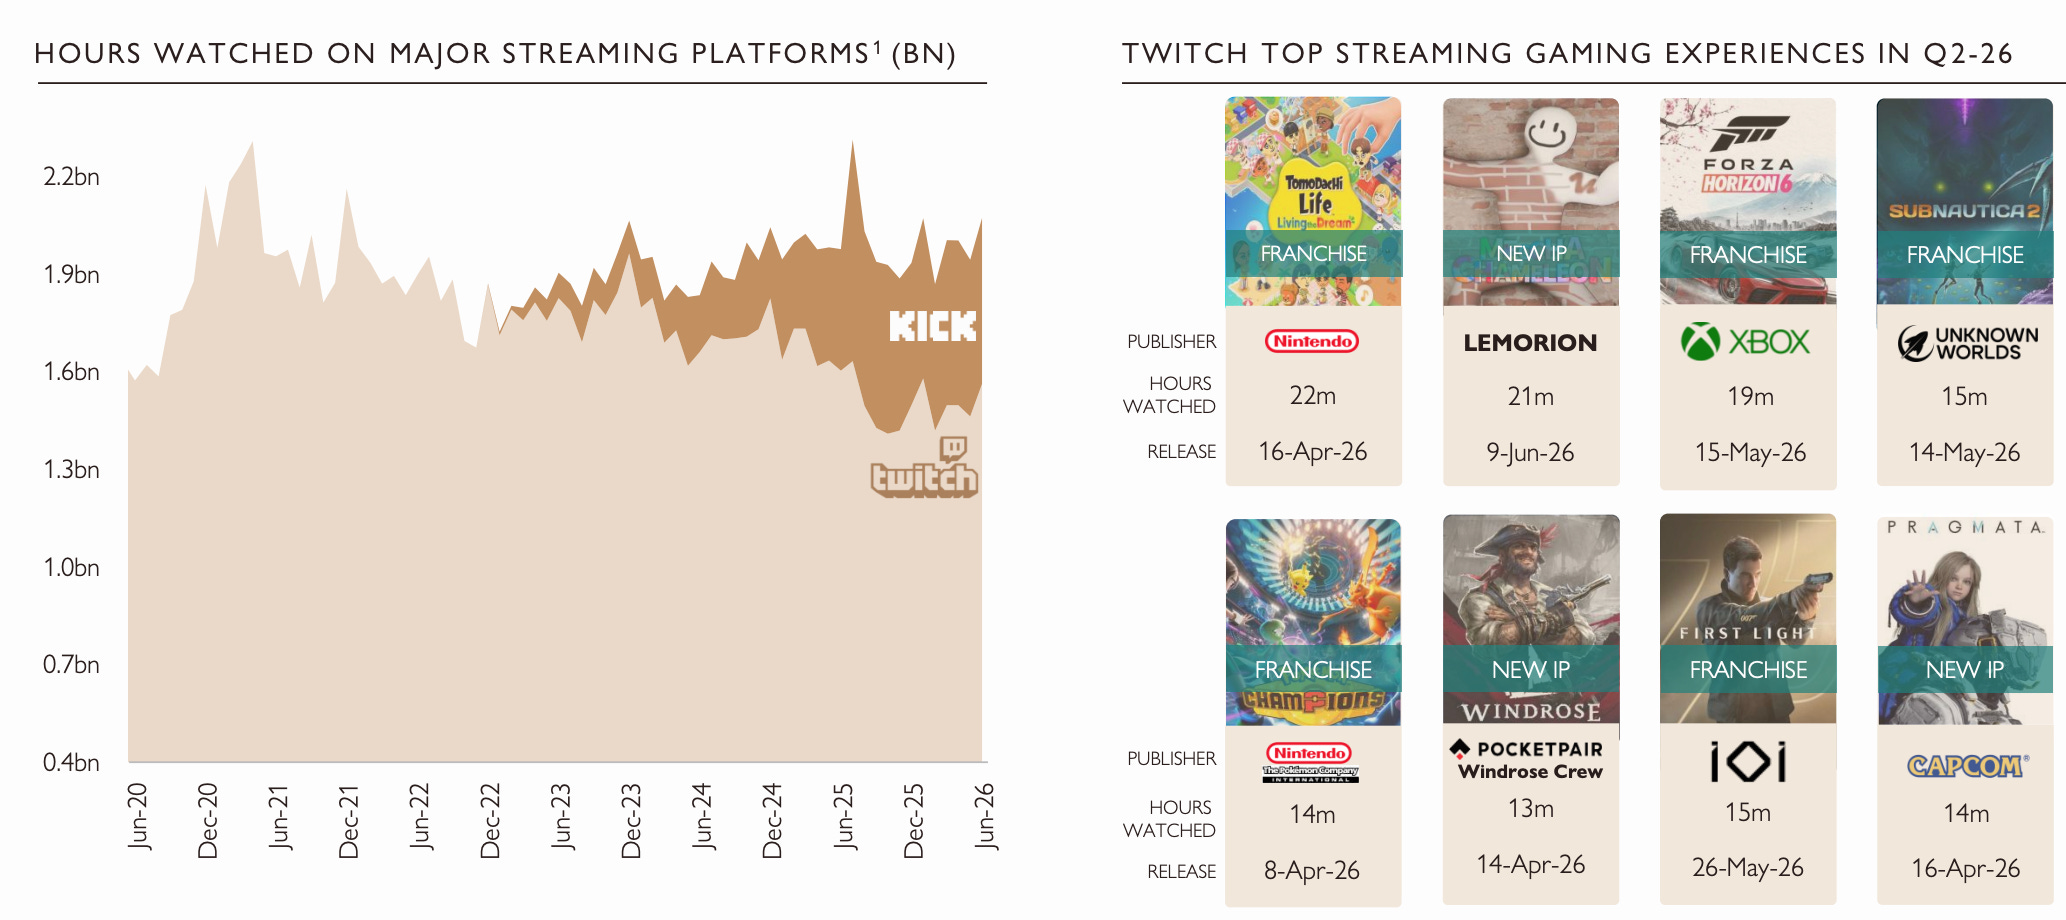
Kick continues to steadily steal Twitch’s audience.
Tomodachi Life: Living the Dream (22 million hours watched), Meccha Chameleon (21 million hours), and Forza Horizon 6 (19 million hours) topped Twitch’s rankings among titles released in Q2’26.
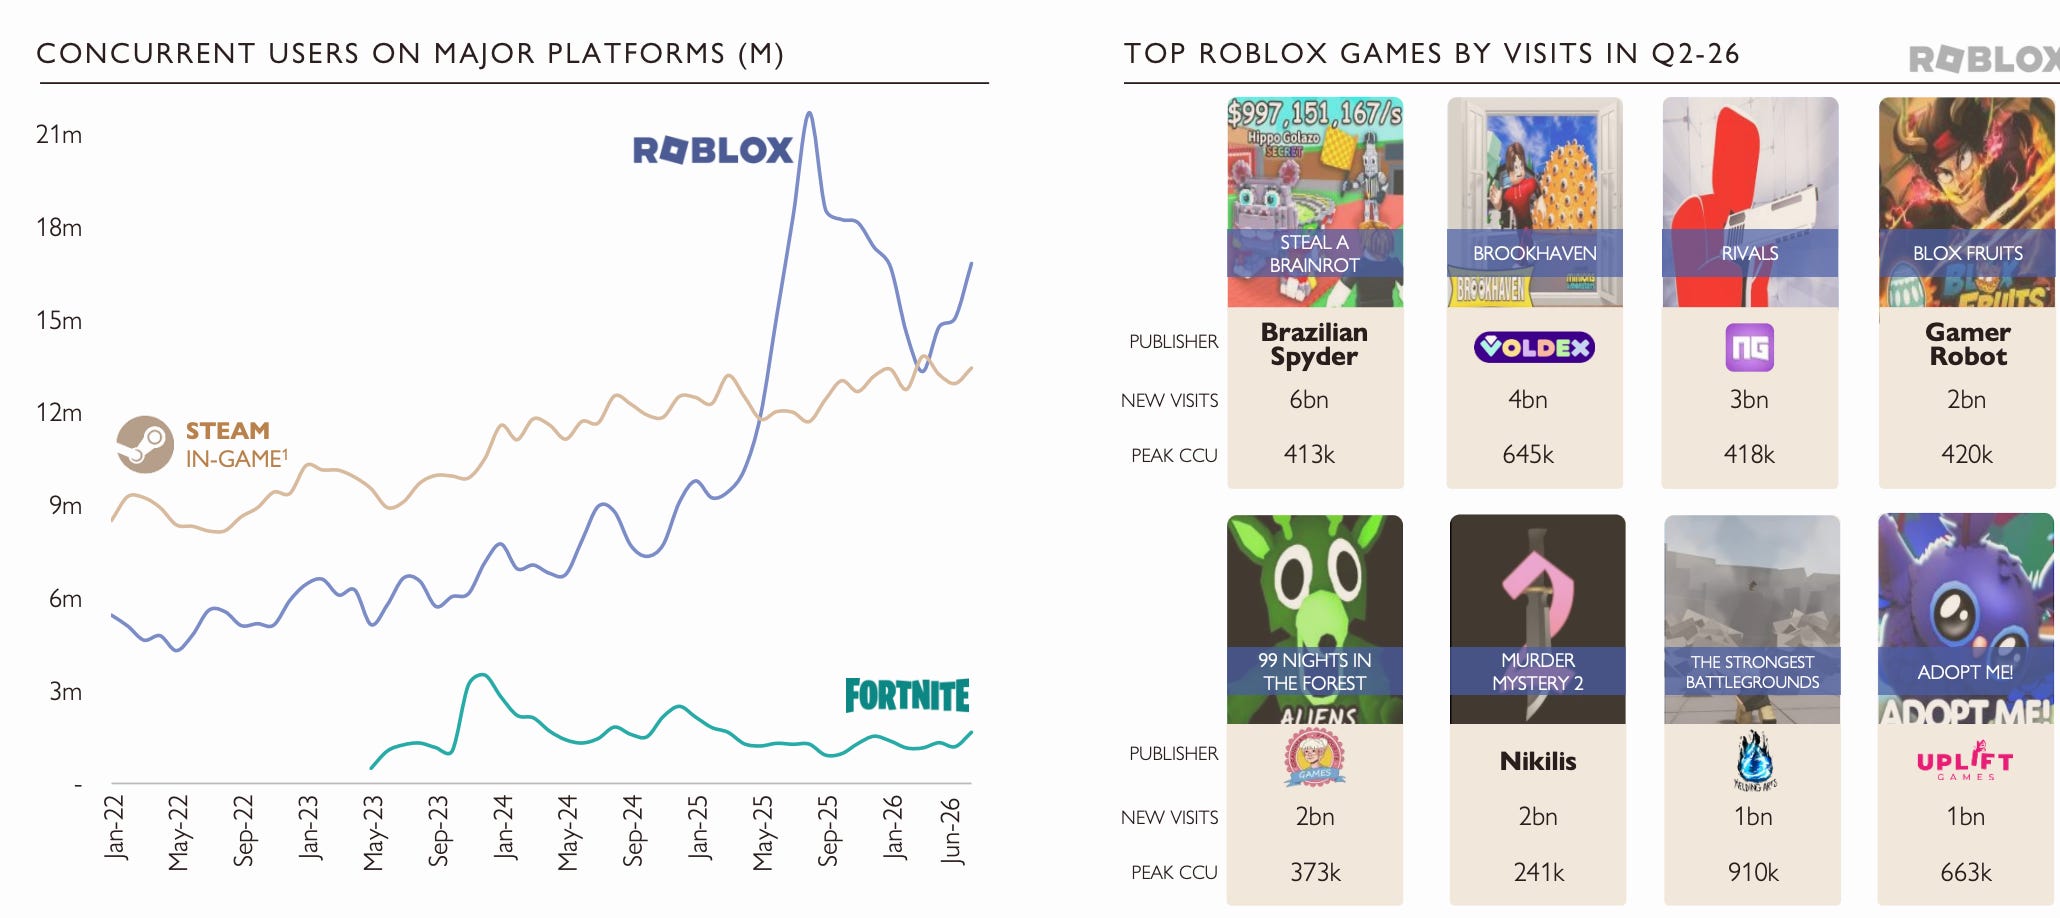
Roblox returned to CCU growth in Q2’26. Fortnite shows the same positive trend, though at an incomparably smaller scale.
Steal a Brainrot, Brookhaven, and Rivals remain Roblox’s top games by visits in Q2’26.
M&A Market
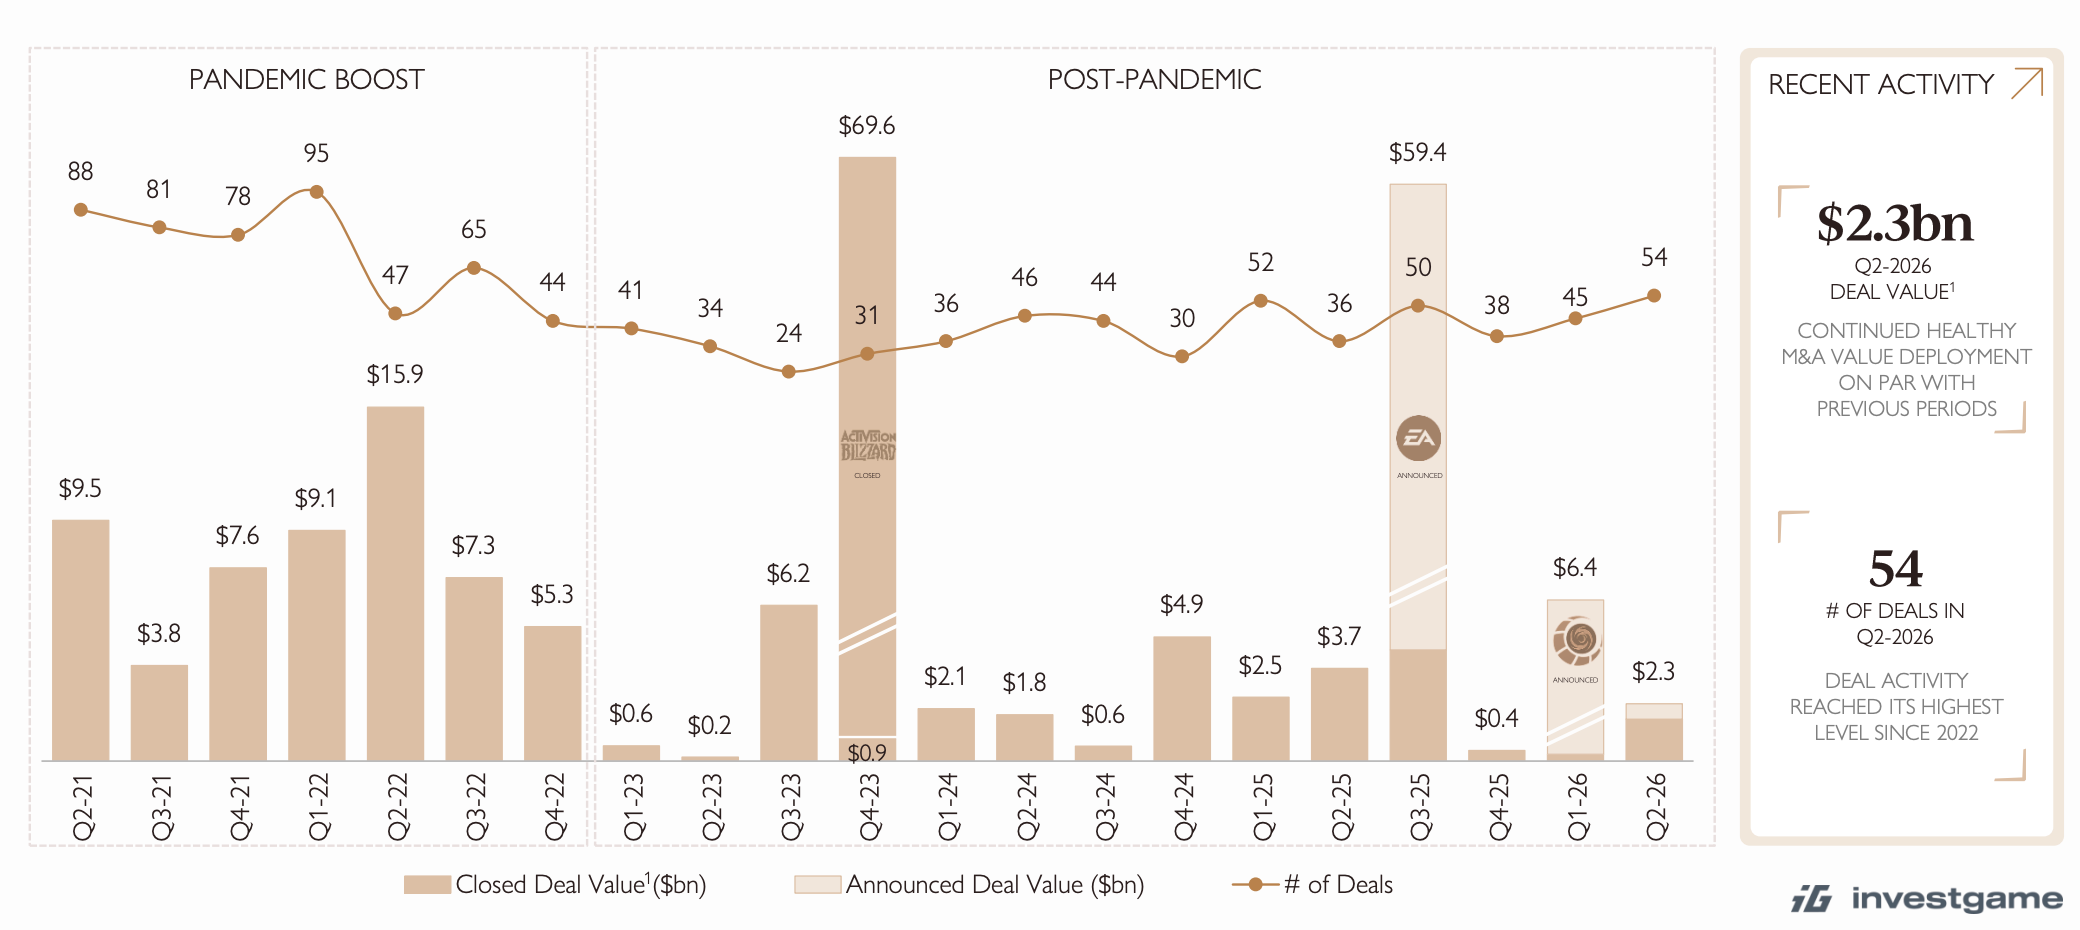
54 deals worth $2.3 billion closed in Q2 2026 - the highest deal count since 2022. The quarter’s headline deal was the closing of the ~$1 billion Loom acquisition; the ~$0.6 billion sale of WeMade’s founder’s stake was also announced.
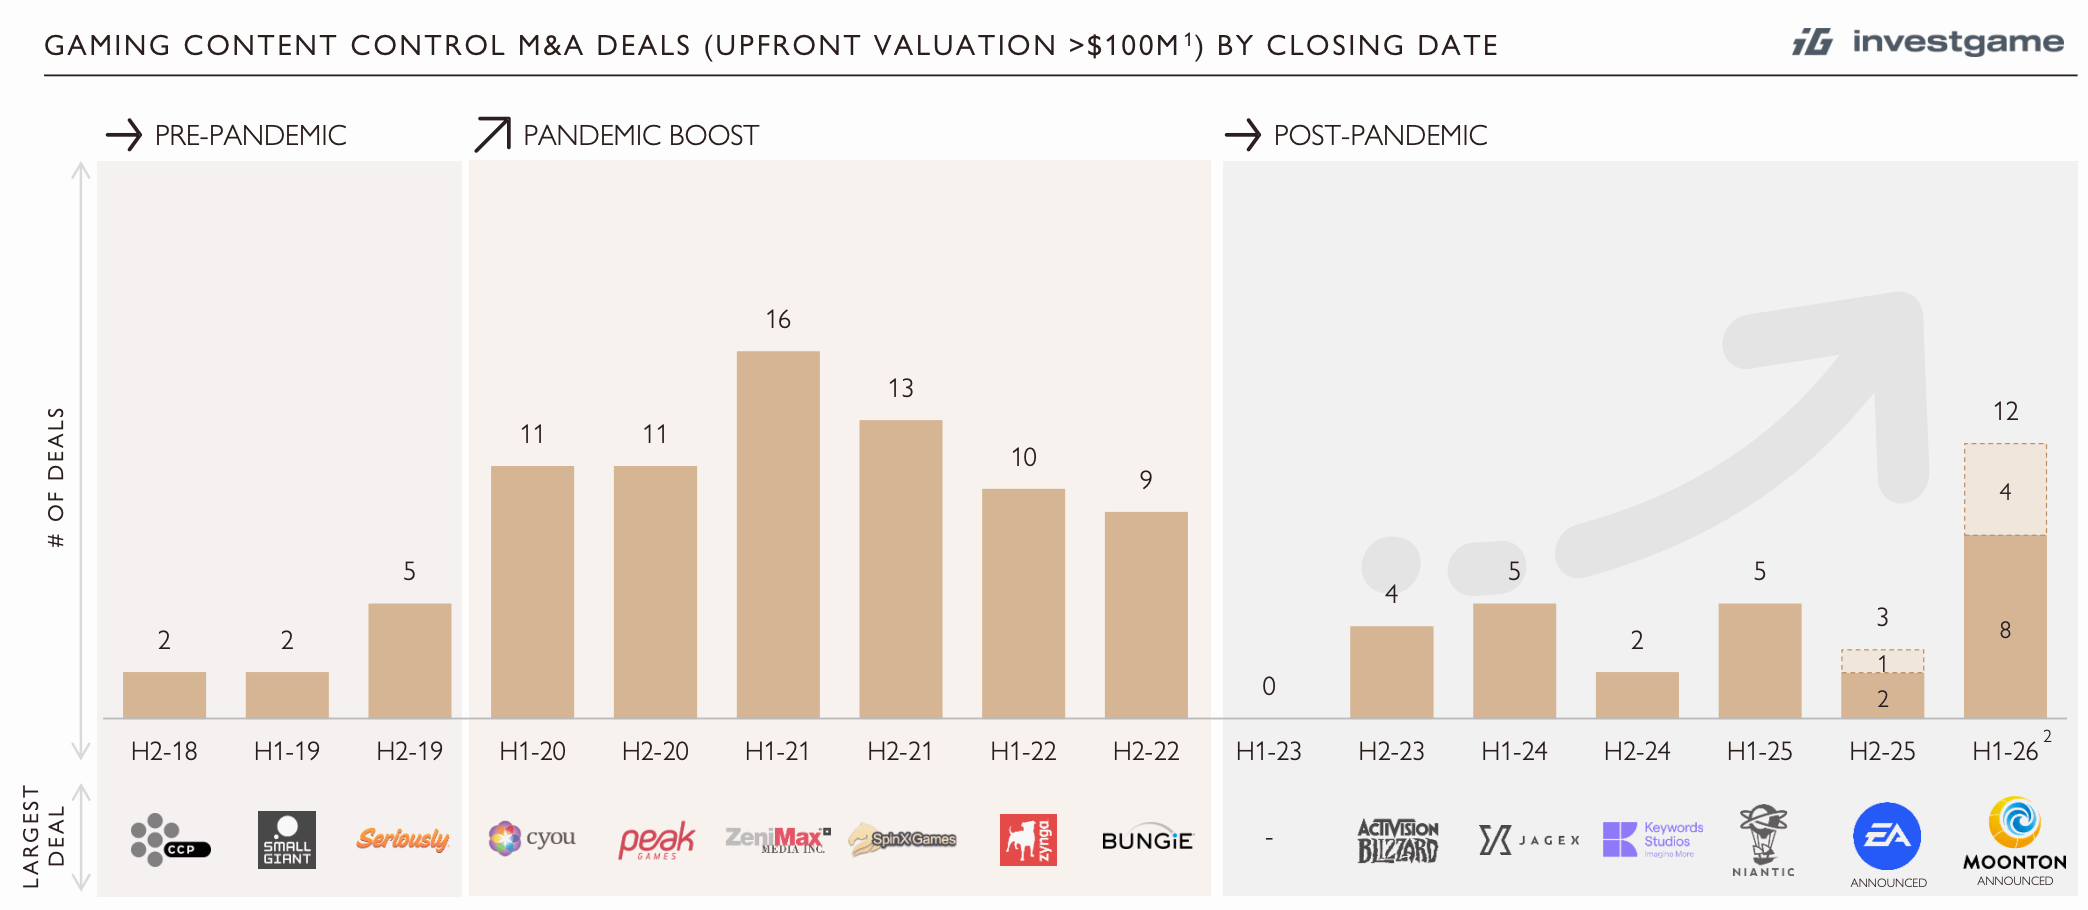
Content M&A deals with game studios valued above $100M hit their highest deal count since the pandemic boom.
Demand is strong for PC games (the Playstack, Fenris Creations, and The Fun Pimps deals) and casual mobile studios.
❗️I’m not sure it’s right to classify JustPlay as a game studio. The company does have development studios, but to me it reads more like AdTech.
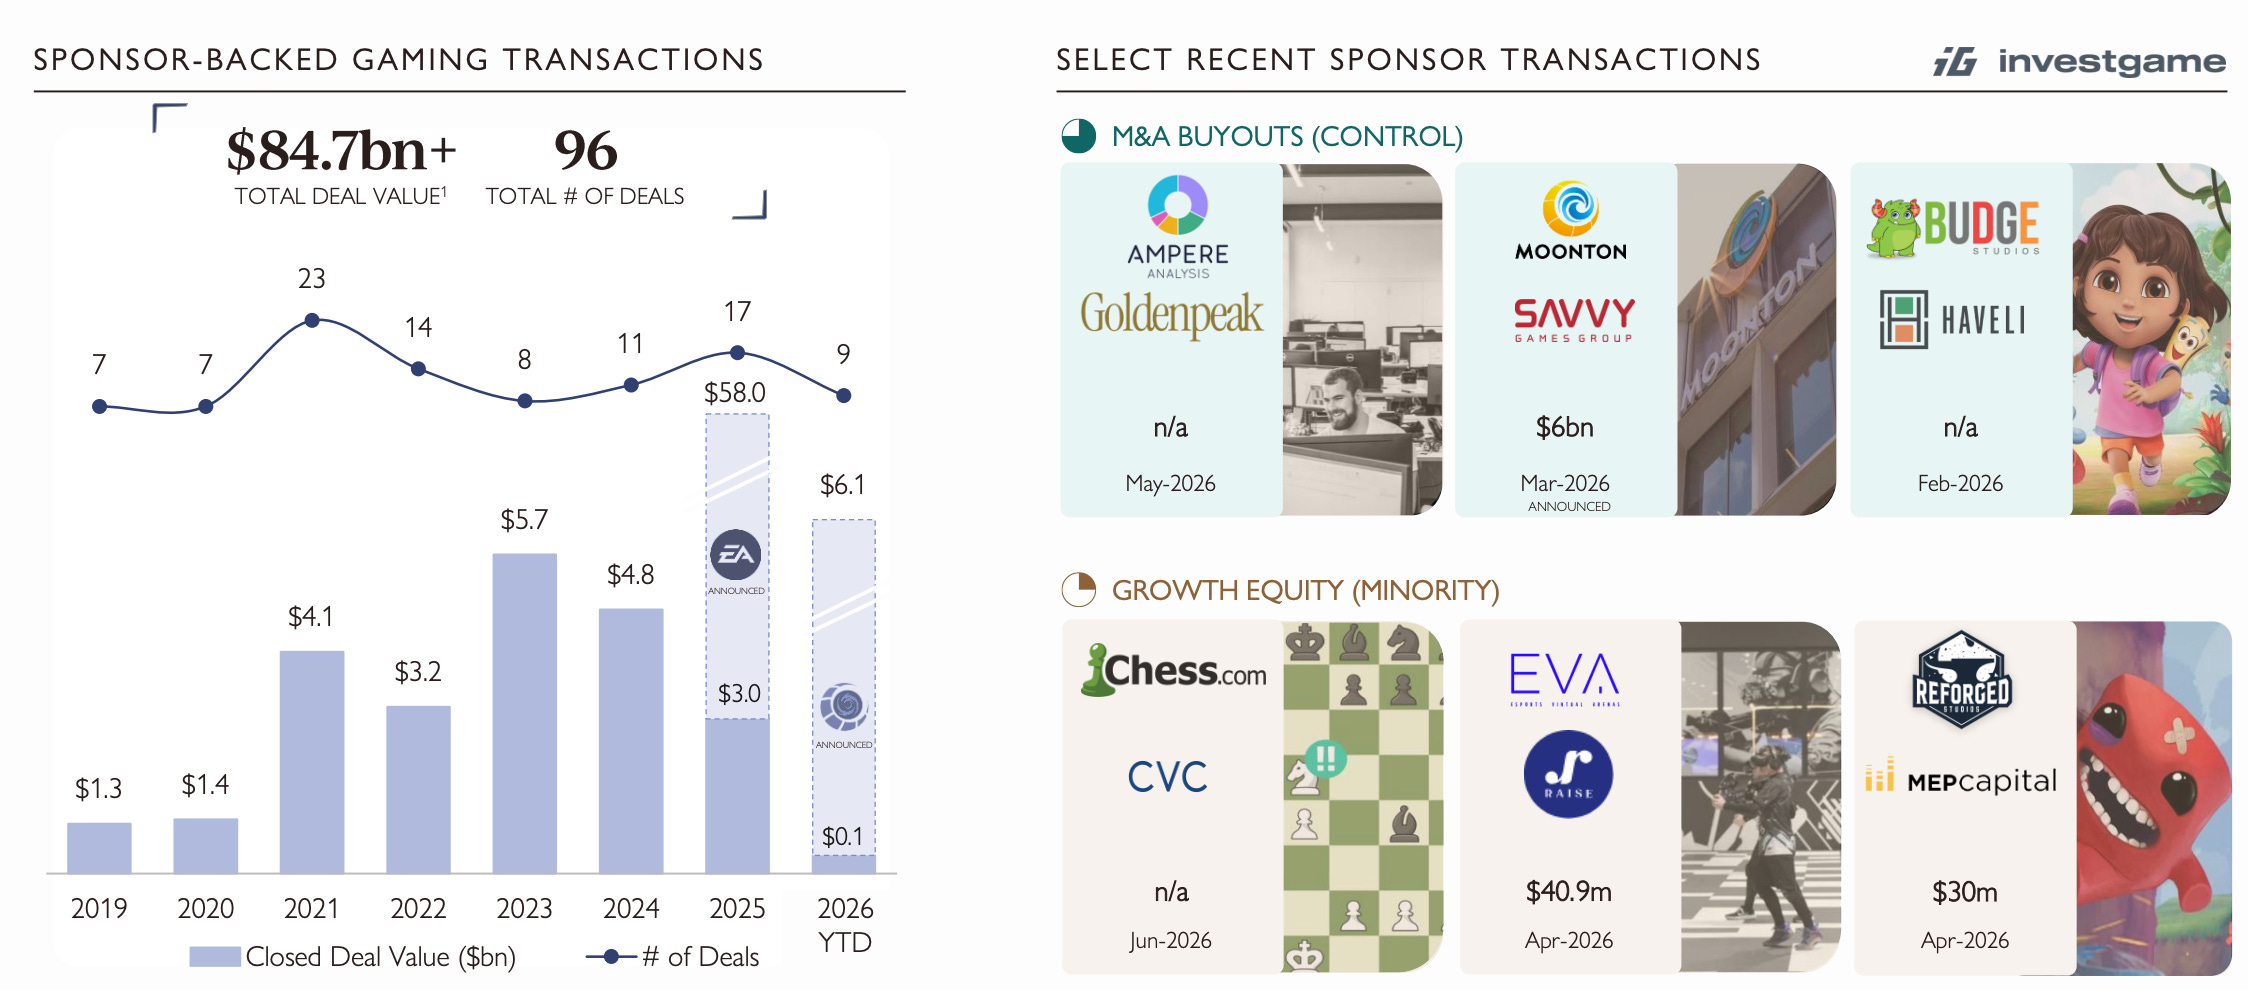
Cumulative deal value involving private-equity sponsors over the last 7 years topped $84.7 billion, across 96 deals.
Public markets
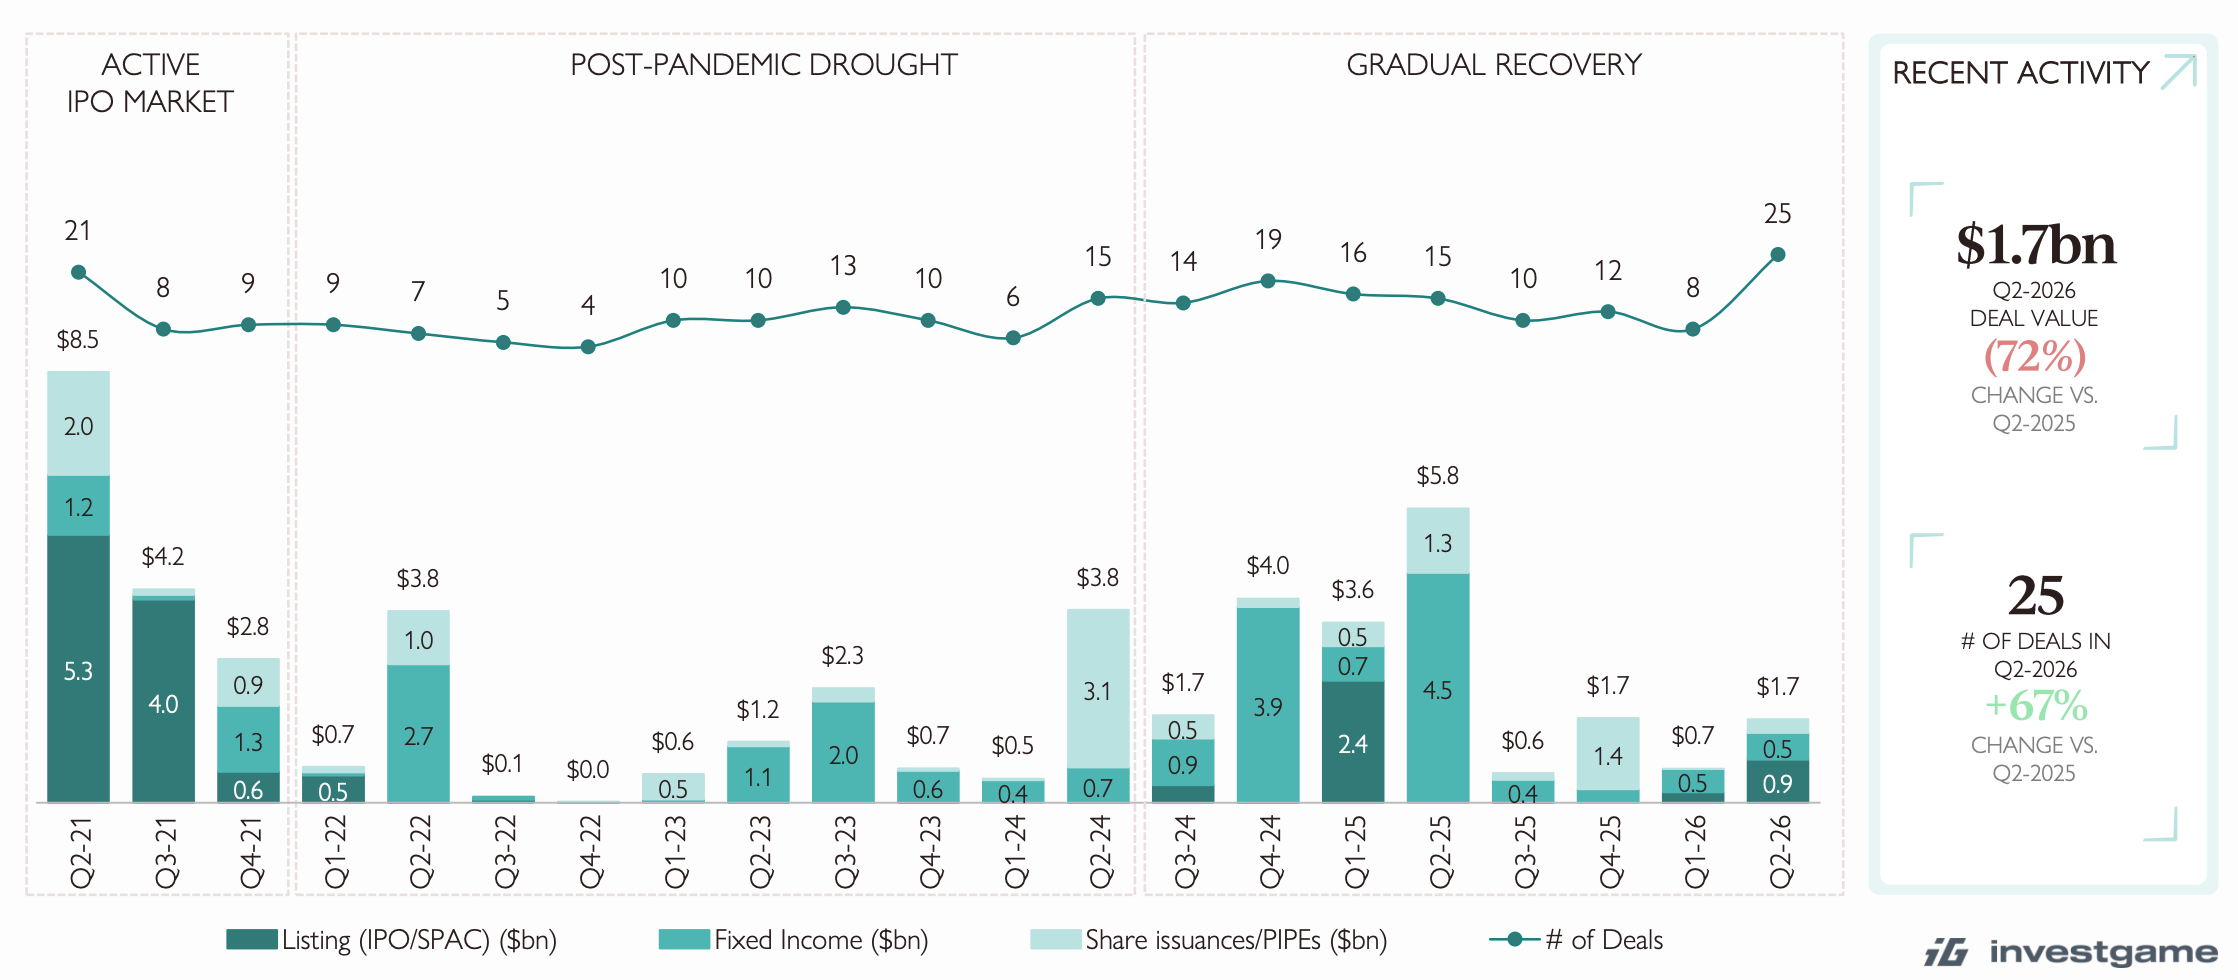
The number of public market deals rose 67% YoY in Q2’26, to 25.
But the value of those deals fell 72% YoY, to $1.7 billion.
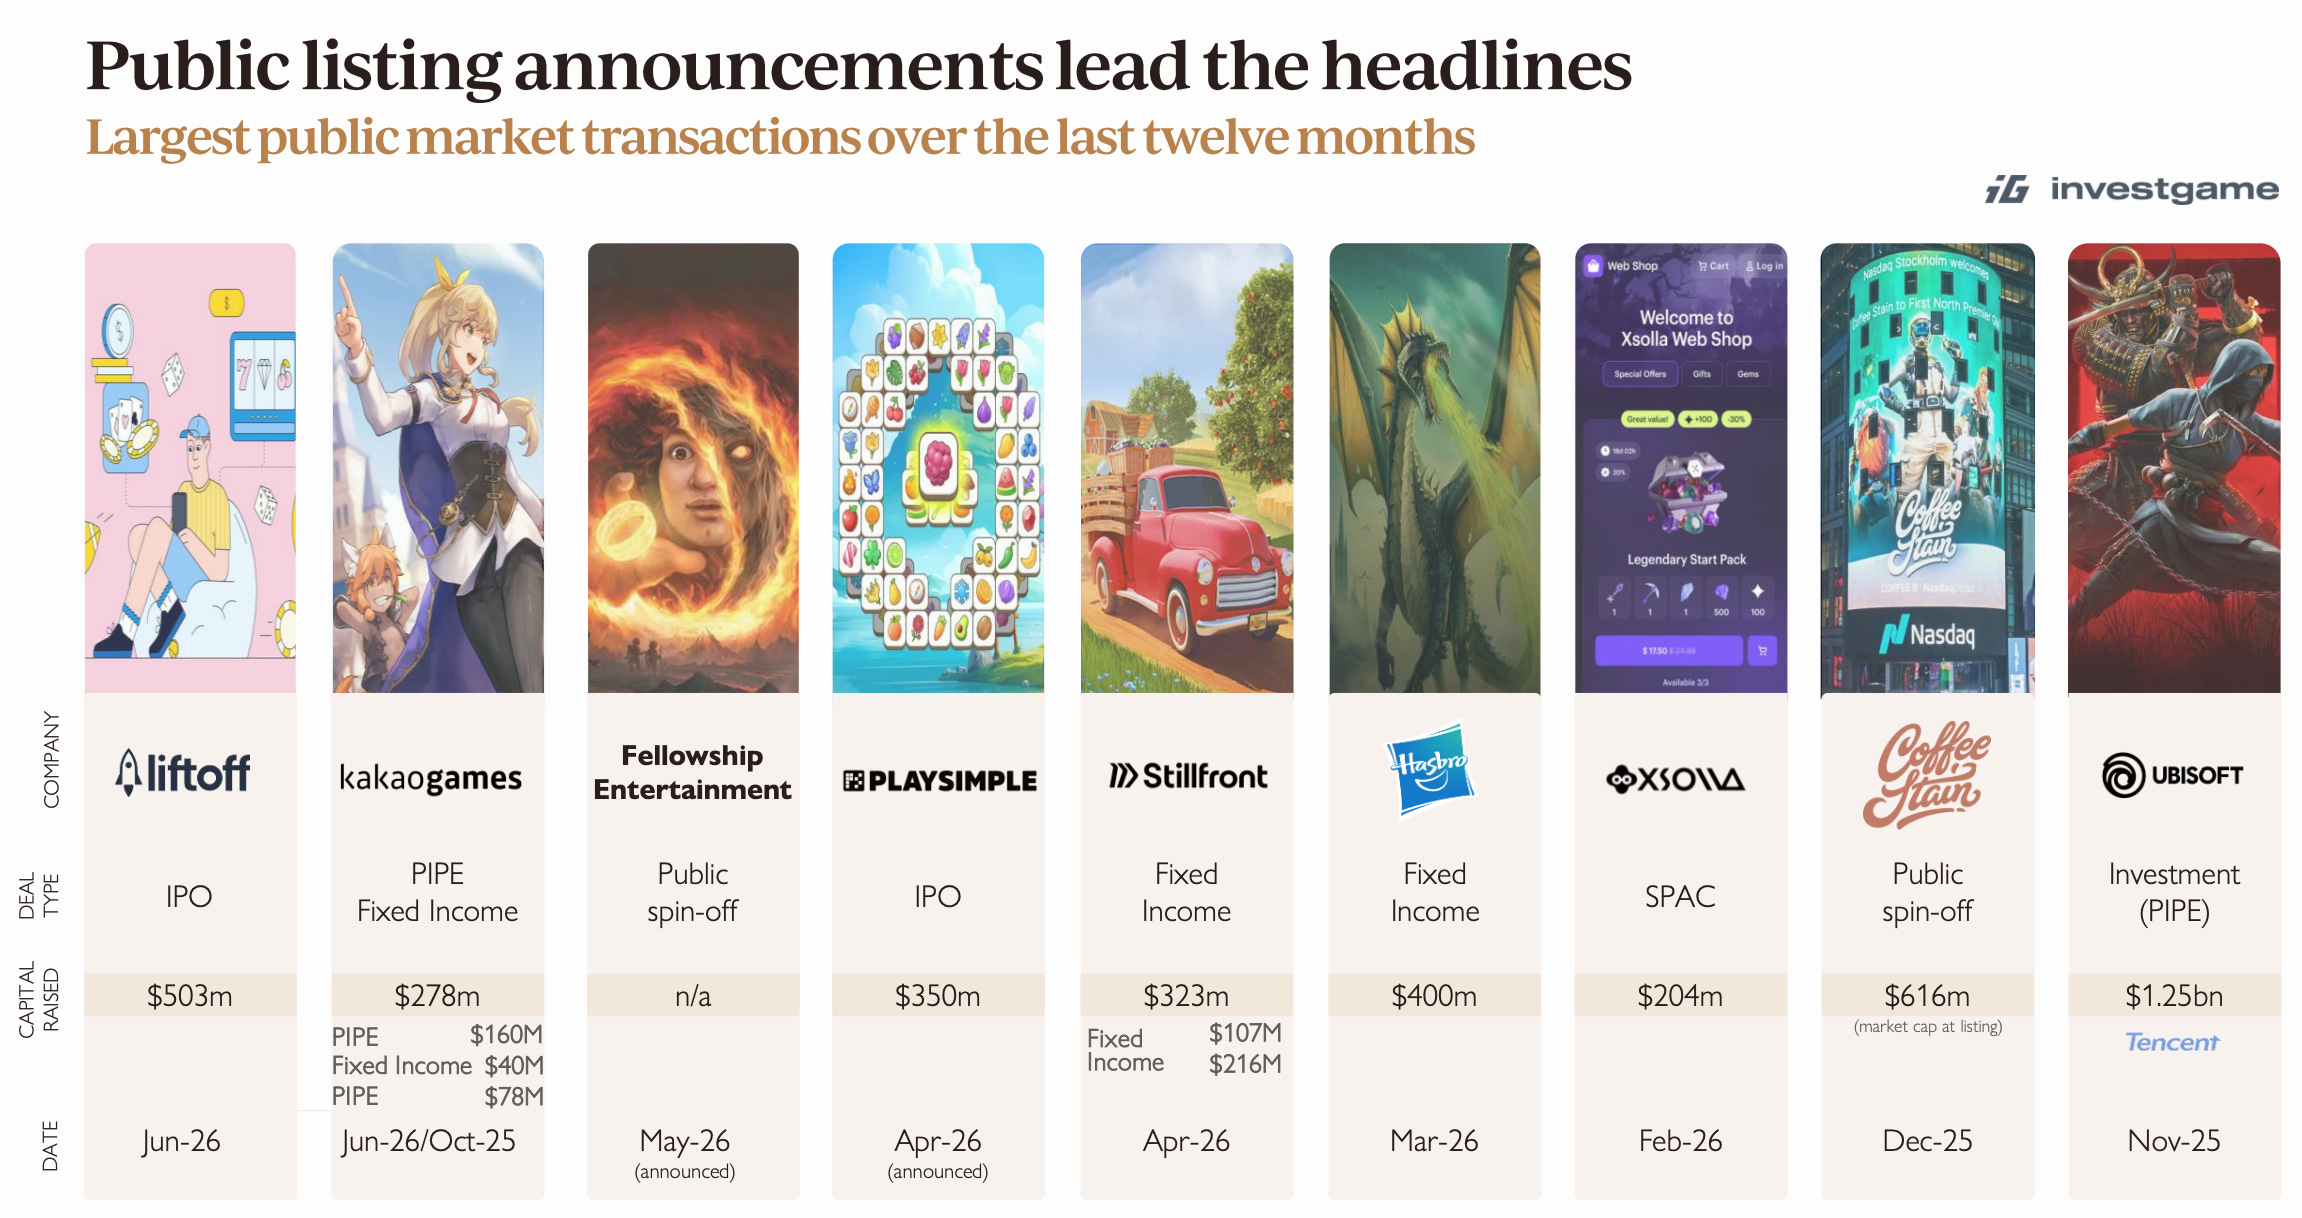
The quarter’s biggest headlines were Liftoff’s IPO (raising $503M), Fellowship Entertainment’s planned spin-off, and PlaySimple’s announced IPO on the Indian exchange.
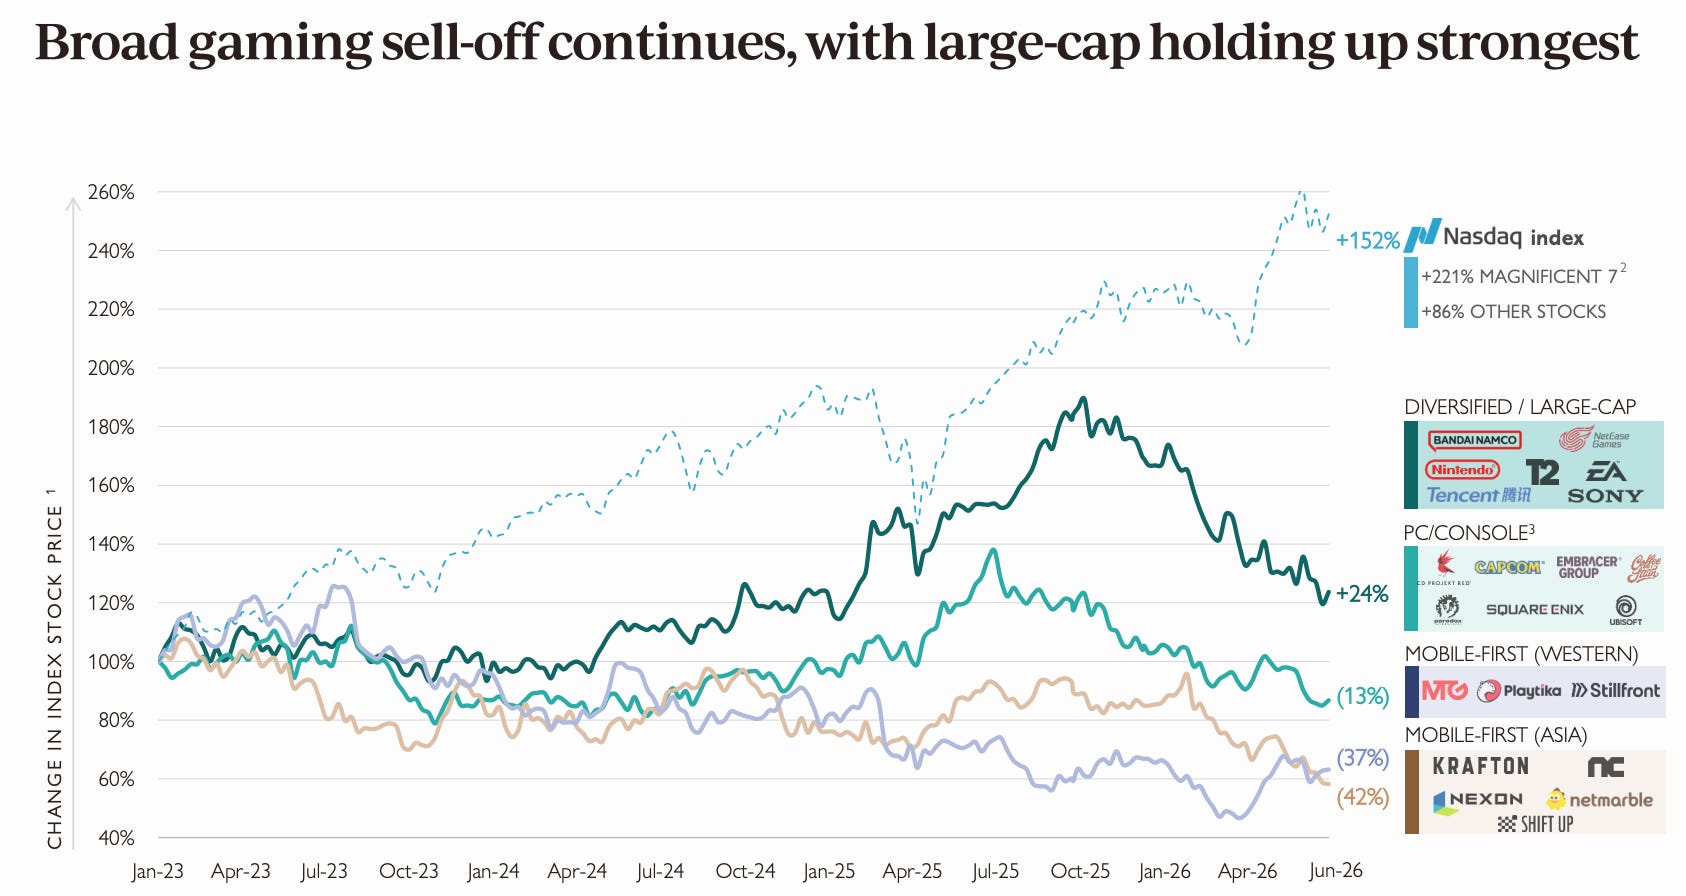
Gaming stocks are having a rough time. Since January 2023, the Nasdaq has outperformed the index of large diversified gaming holdings (Bandai Namco, Nintendo, EA, Sony) by more than 6x. The rest of the sector - mobile companies especially - is in negative territory.
The entire gaming sector is down year-to-date, driven by a range of factors. Still, against that backdrop, Western public mobile companies’ results ticked up slightly in Q2’26.
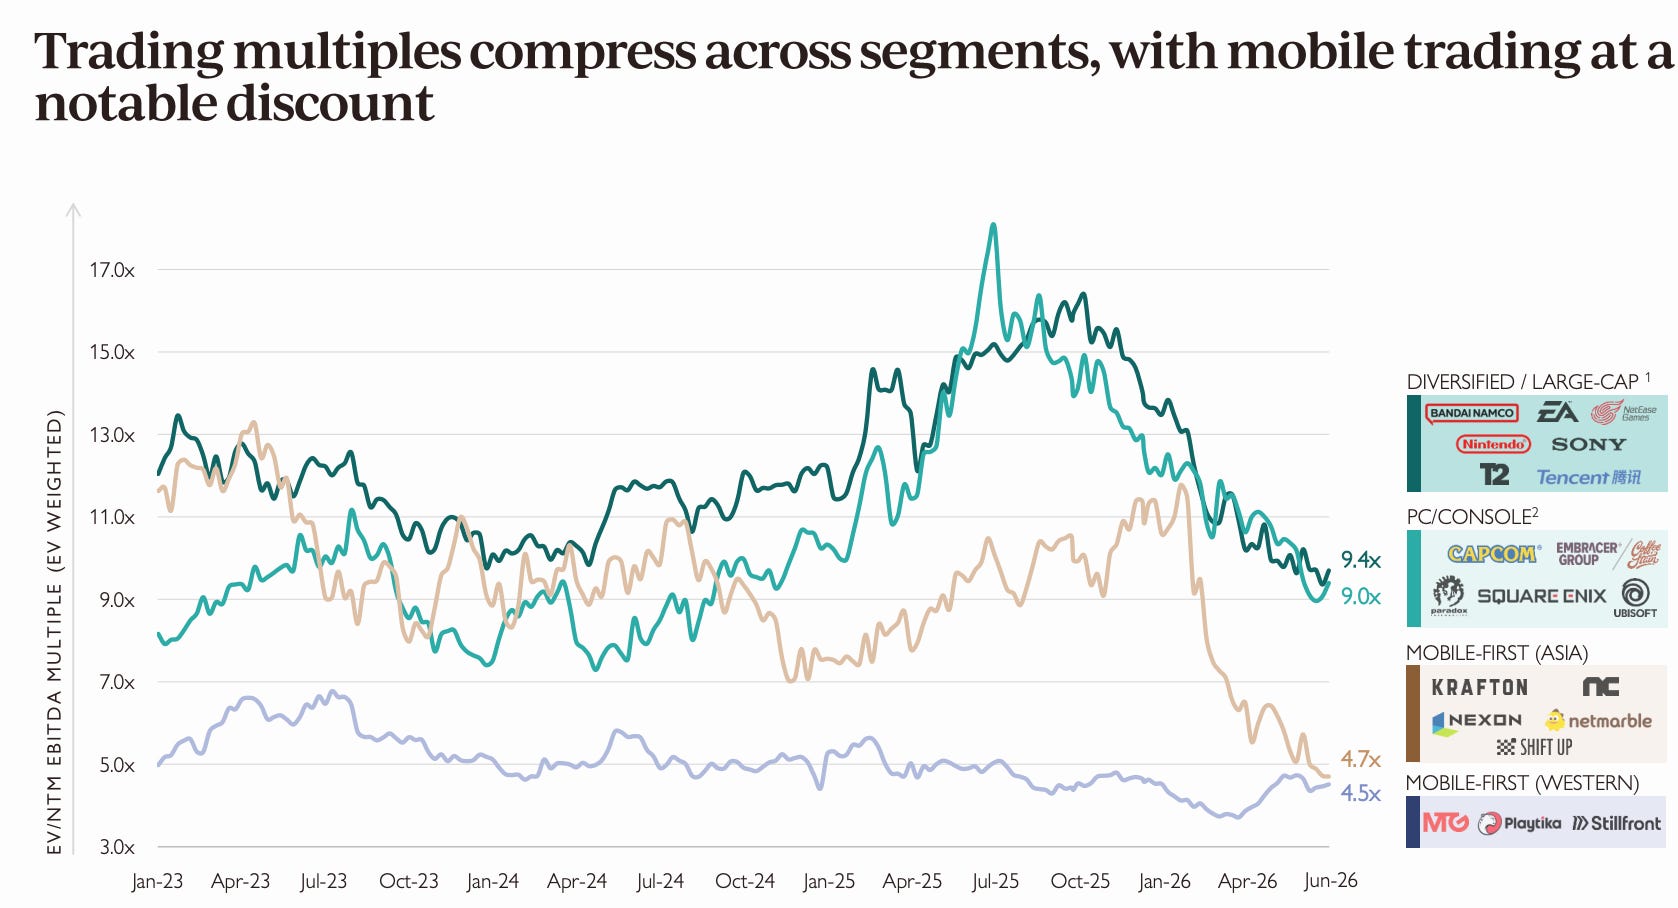
Multiples are compressing across every segment. Diversified holdings trade at the highest premium (9.4x EV/NTM EBITDA). Mobile publishers are valued lowest, in Asia (4.7x) and the West (4.5x).
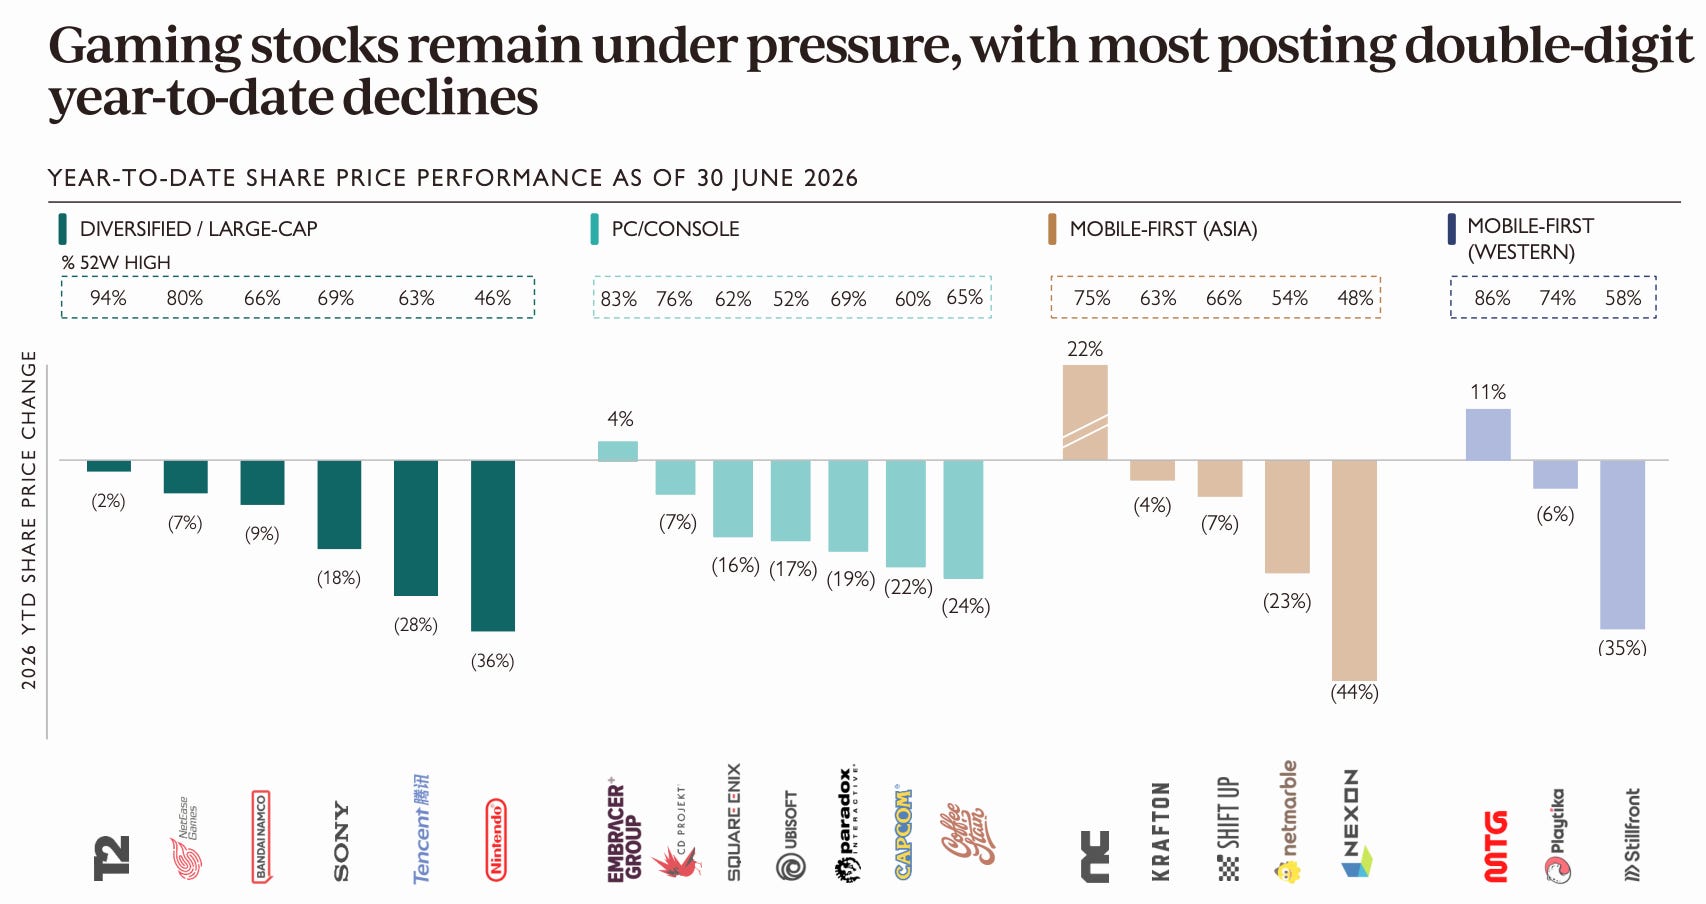
The vast majority of gaming companies have lost value over the last 12 months.
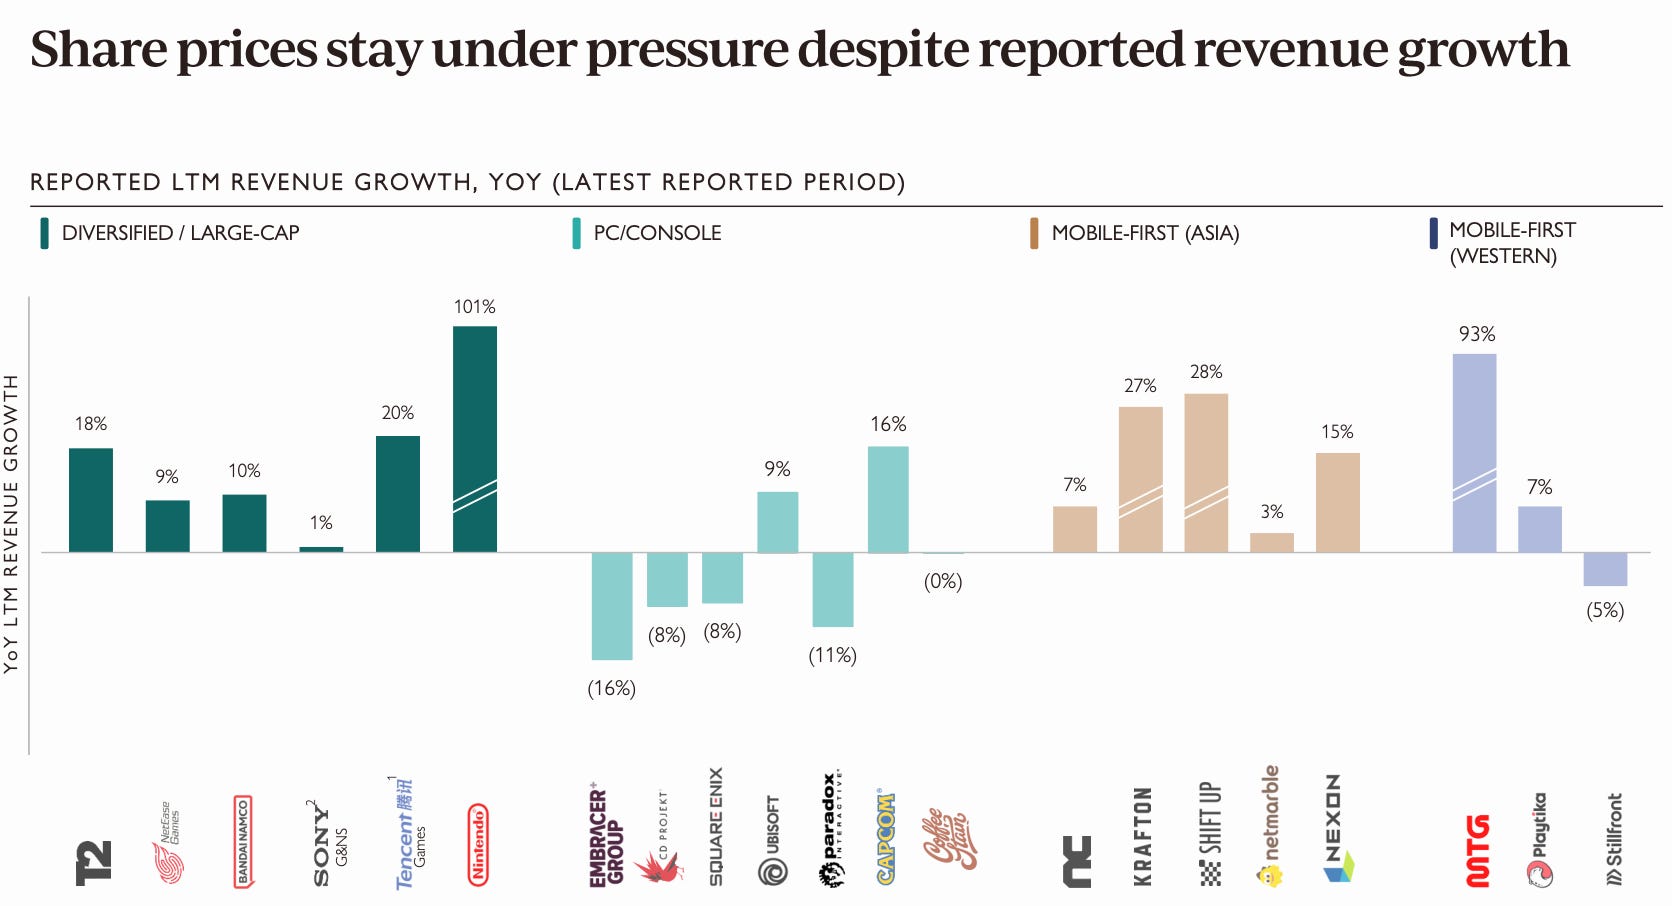
That’s happening even as most companies post fairly solid revenue growth in their earnings reports.
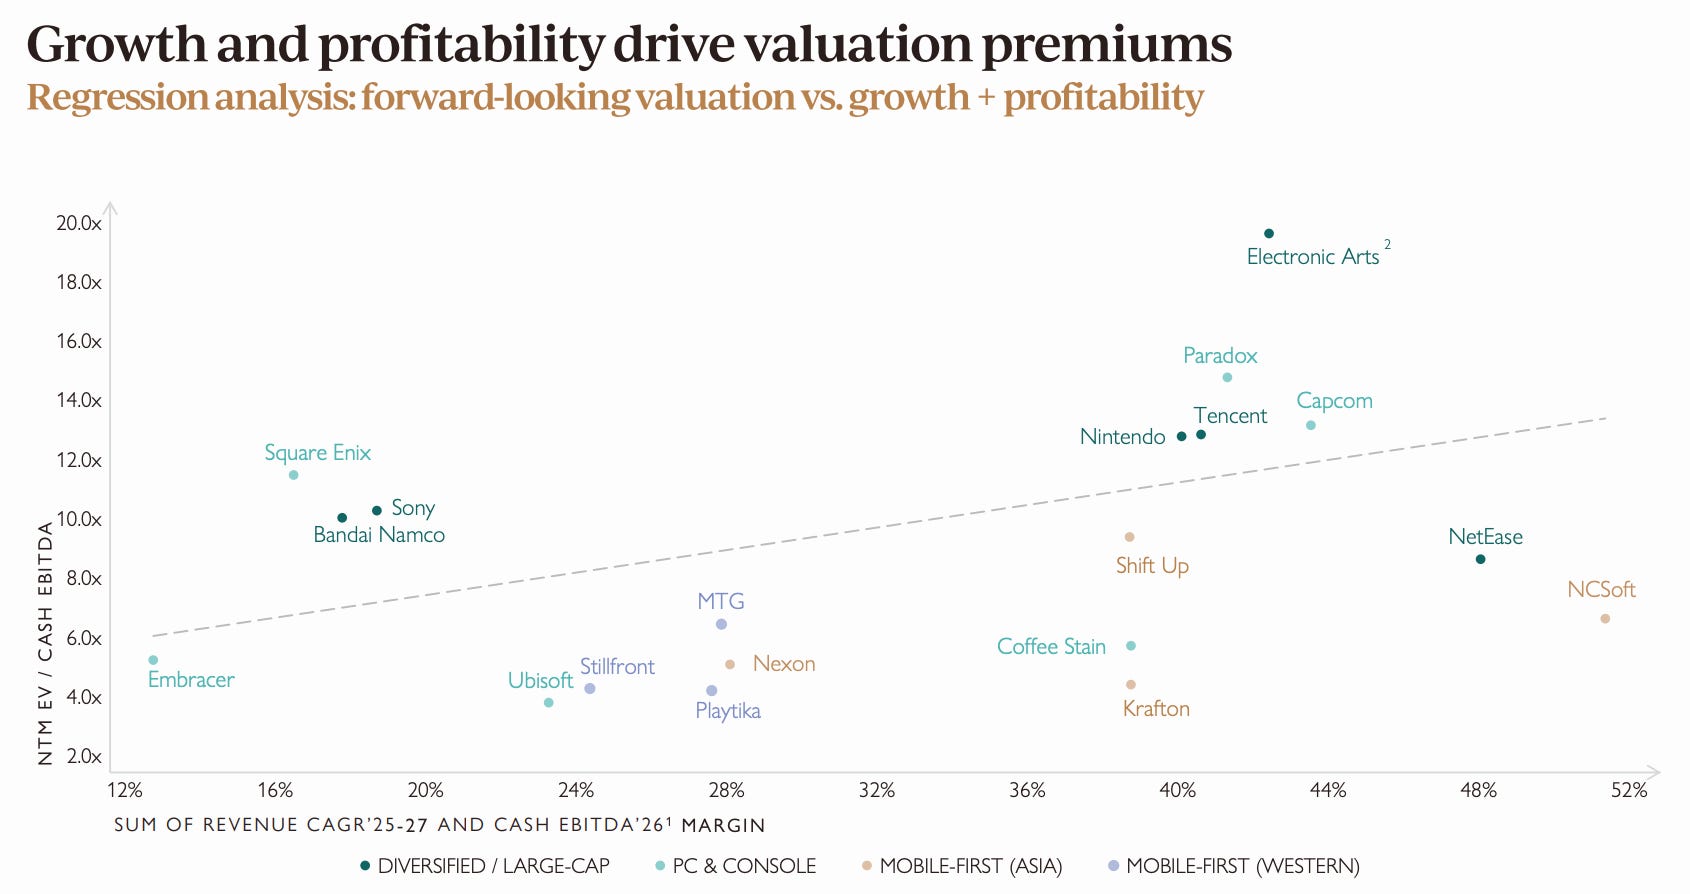
Electronic Arts, Capcom, Paradox Interactive, Tencent, and Nintendo stand out as the best-positioned names in the market.
A word from our sponsor
Still paying for impressions and clicks that never convert? Advertise your PC game with PWN Games! With our CPA model, you only pay when a player installs, engages, or pays. 250+ PC games promoted, 42M+ players acquired, 10 years in the business. Trusted by top PC game publishers worldwide.
Private investments
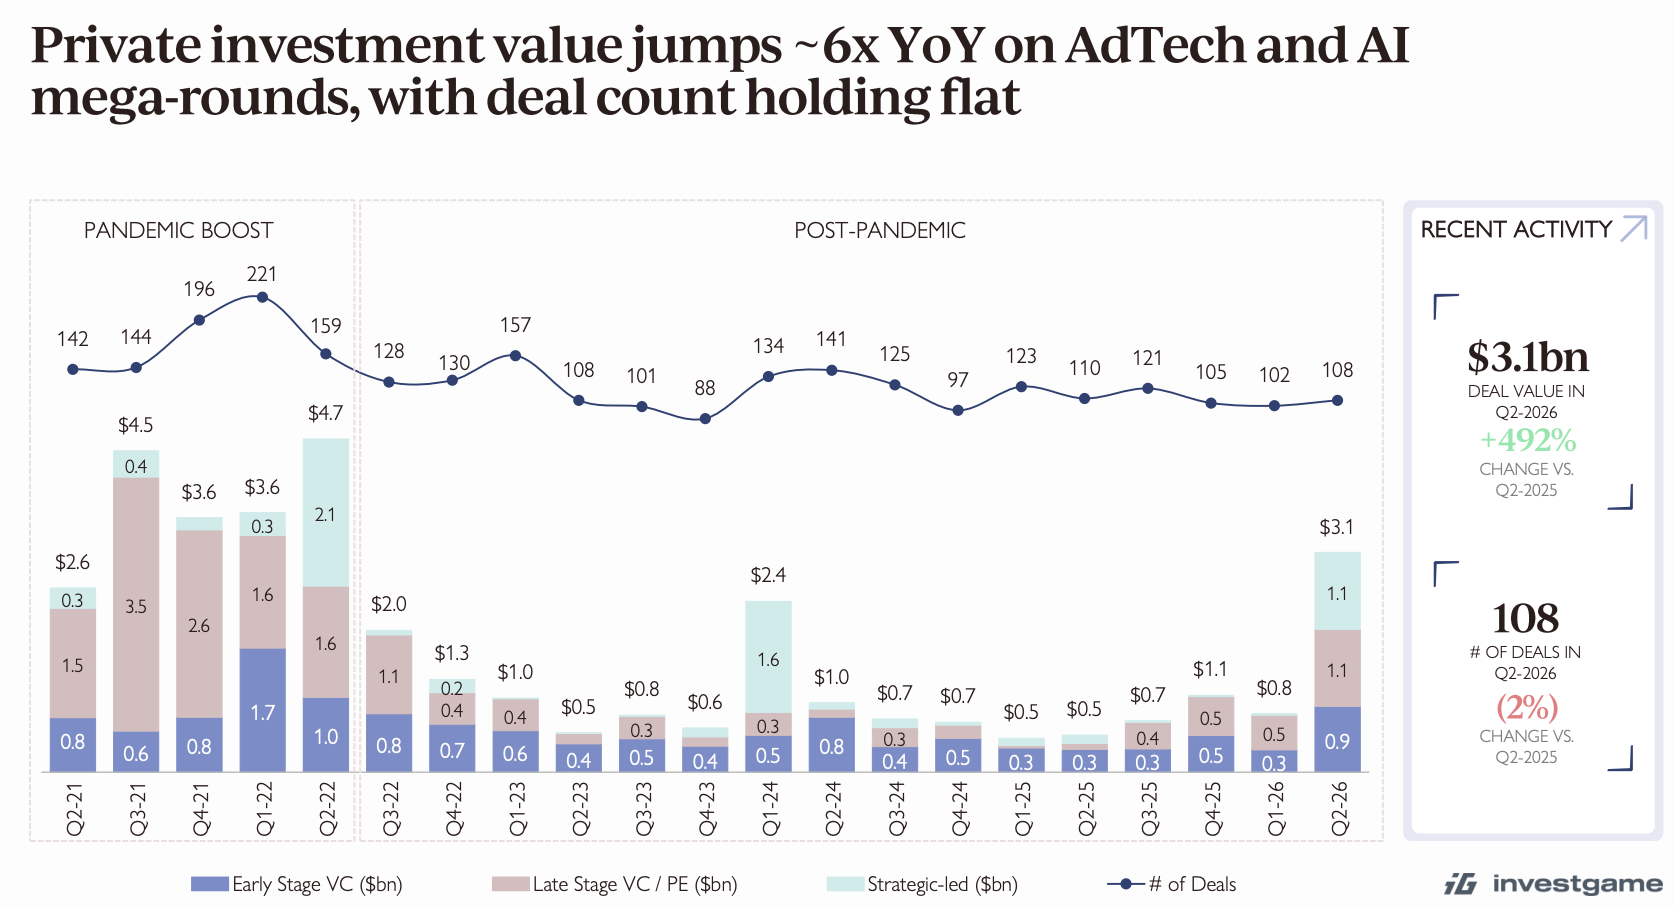
Private investment value jumped nearly 6x YoY to $3.1 billion, while deal count has stayed stable over the past several quarters (108 in Q2’26).
The jump came from AppsFlyer’s $1 billion round and heavy investment in AI tech (General Intuition, Odyssey, Decart).
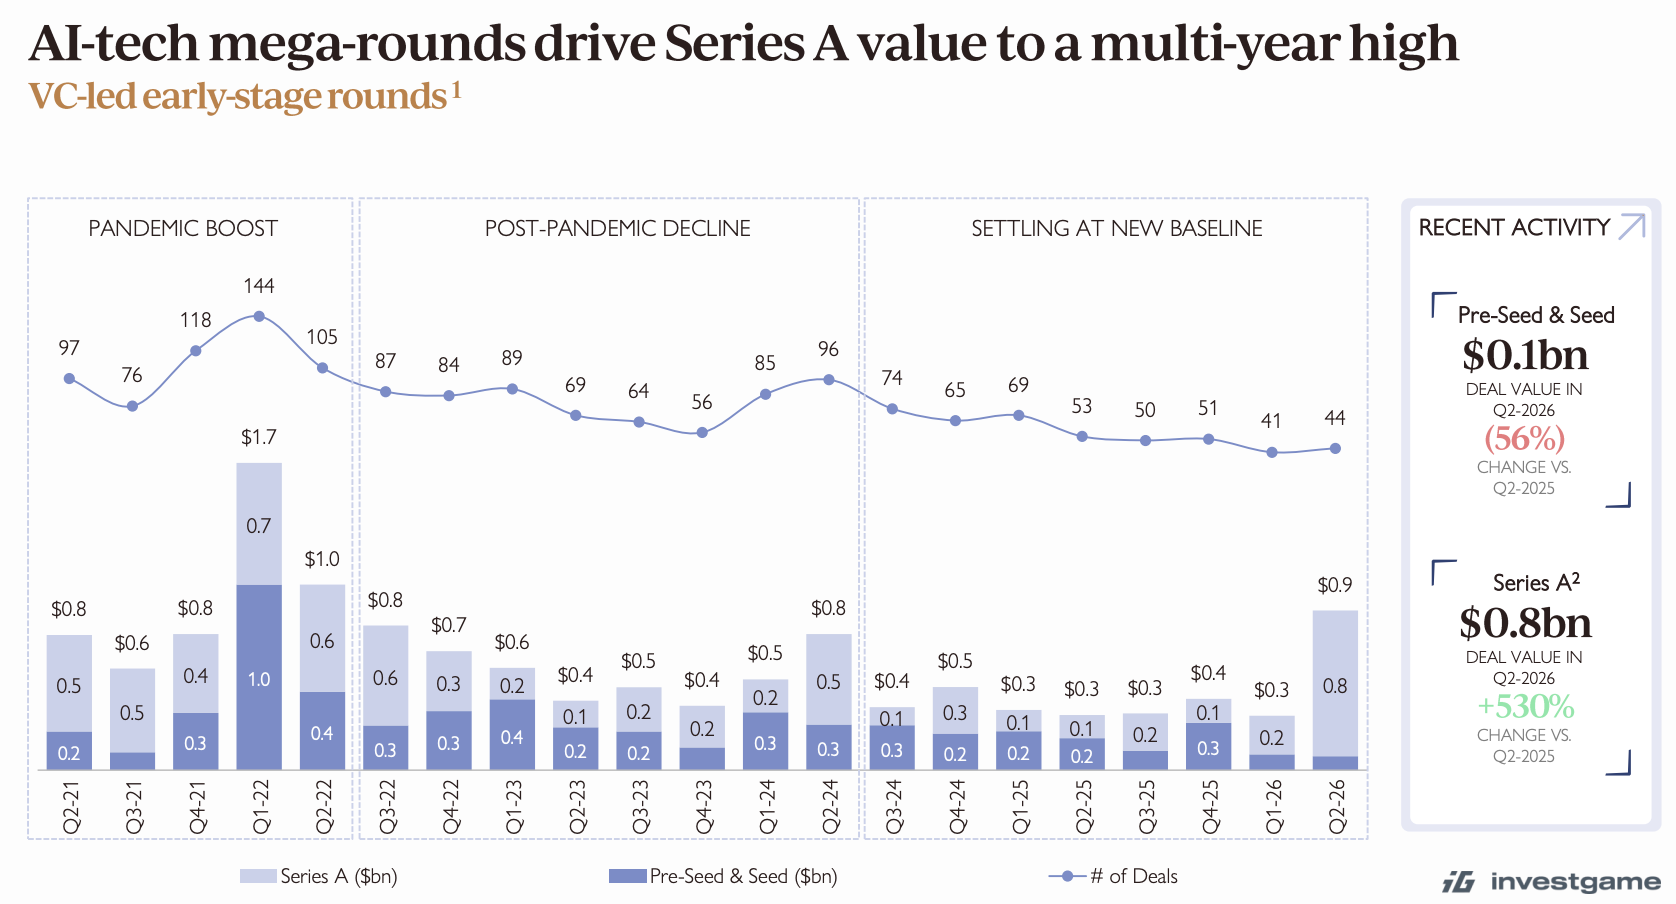
Series A rounds hit a 5-year high - $0.8 billion in Q2 (+530% YoY).
Pre-seed and seed, on the other hand, hit a multi-year low - just $0.1 billion in deals in Q2’26 (-56% YoY).
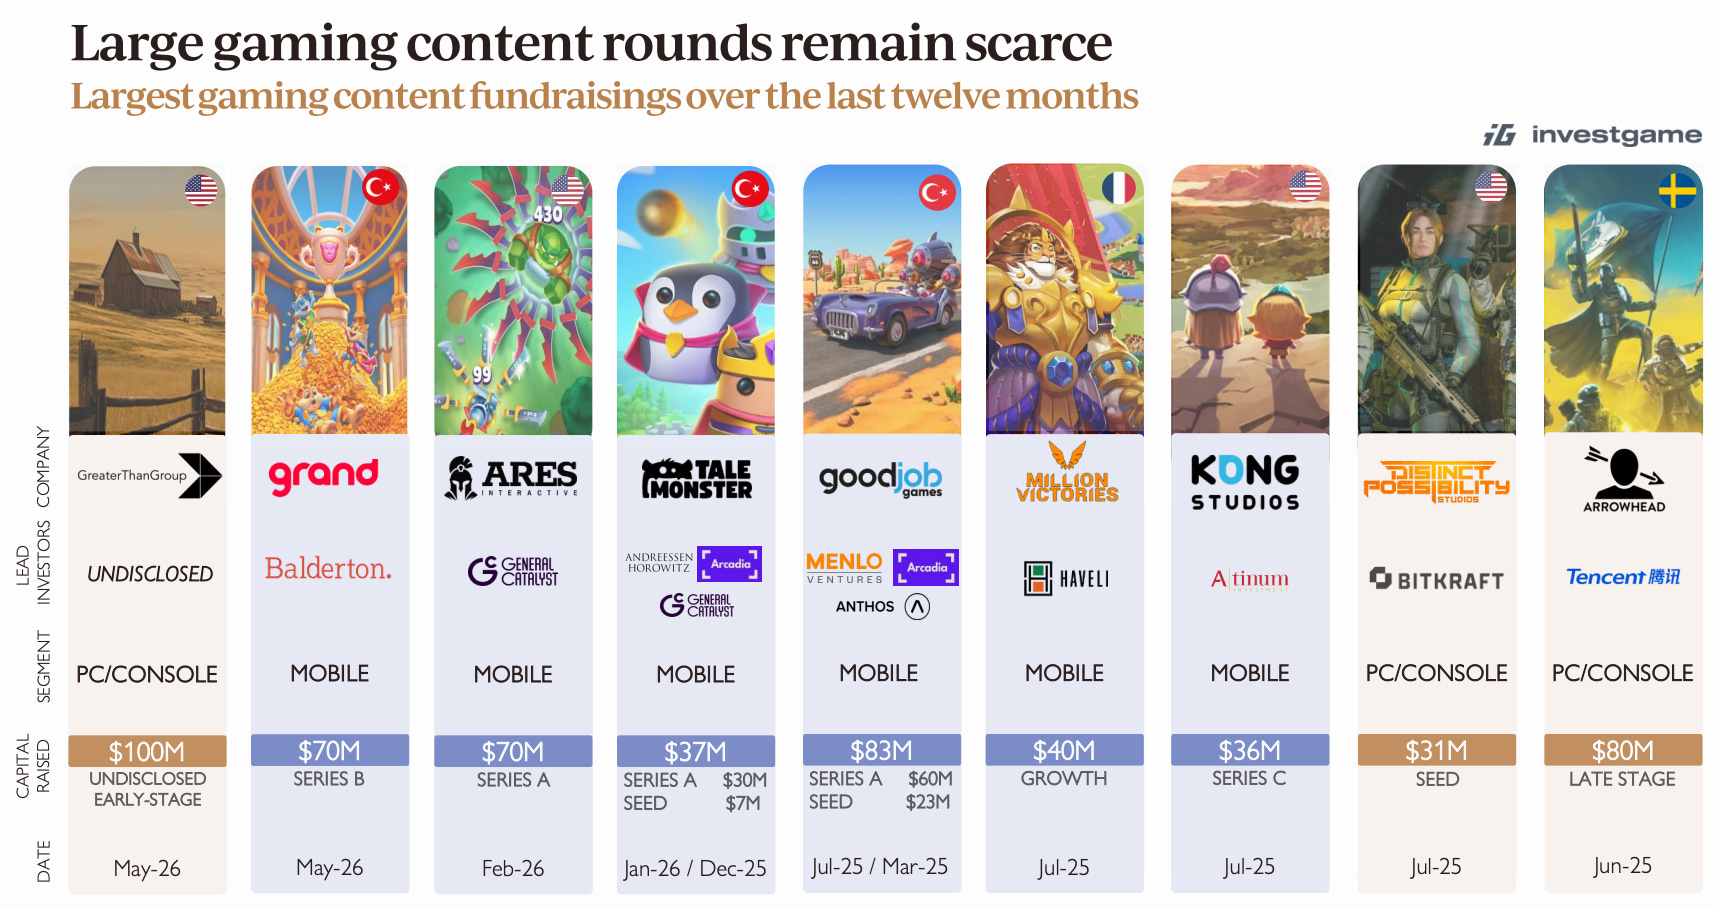
Large rounds specifically for game content remain rare. As noted above, most of the activity is going into tech.
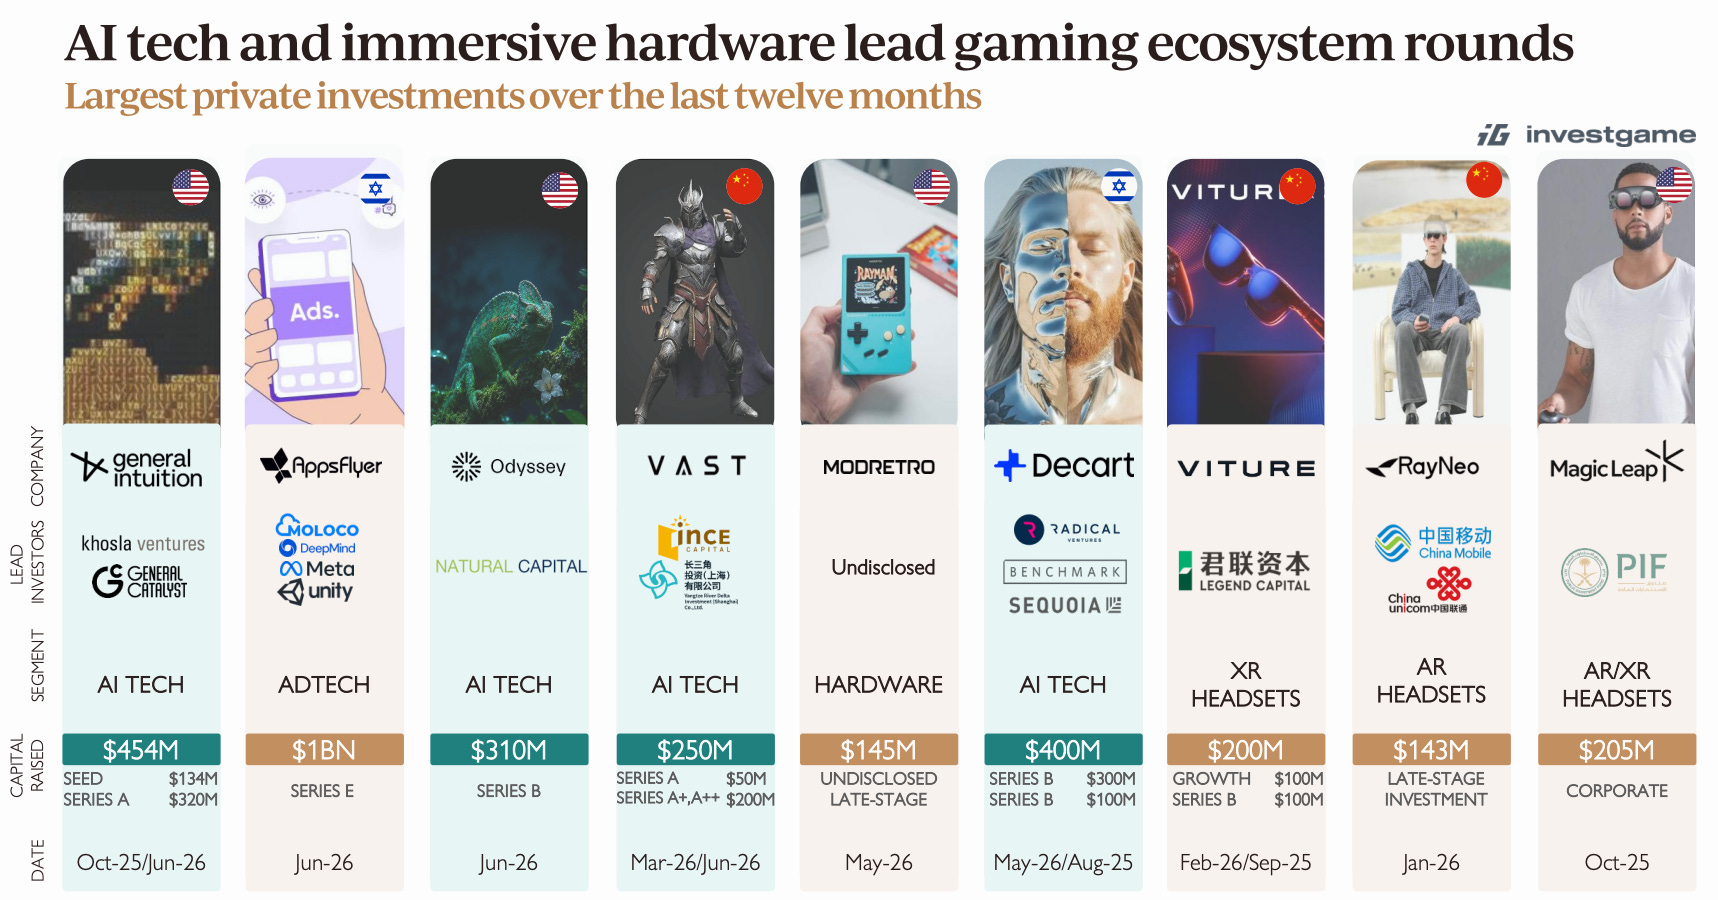
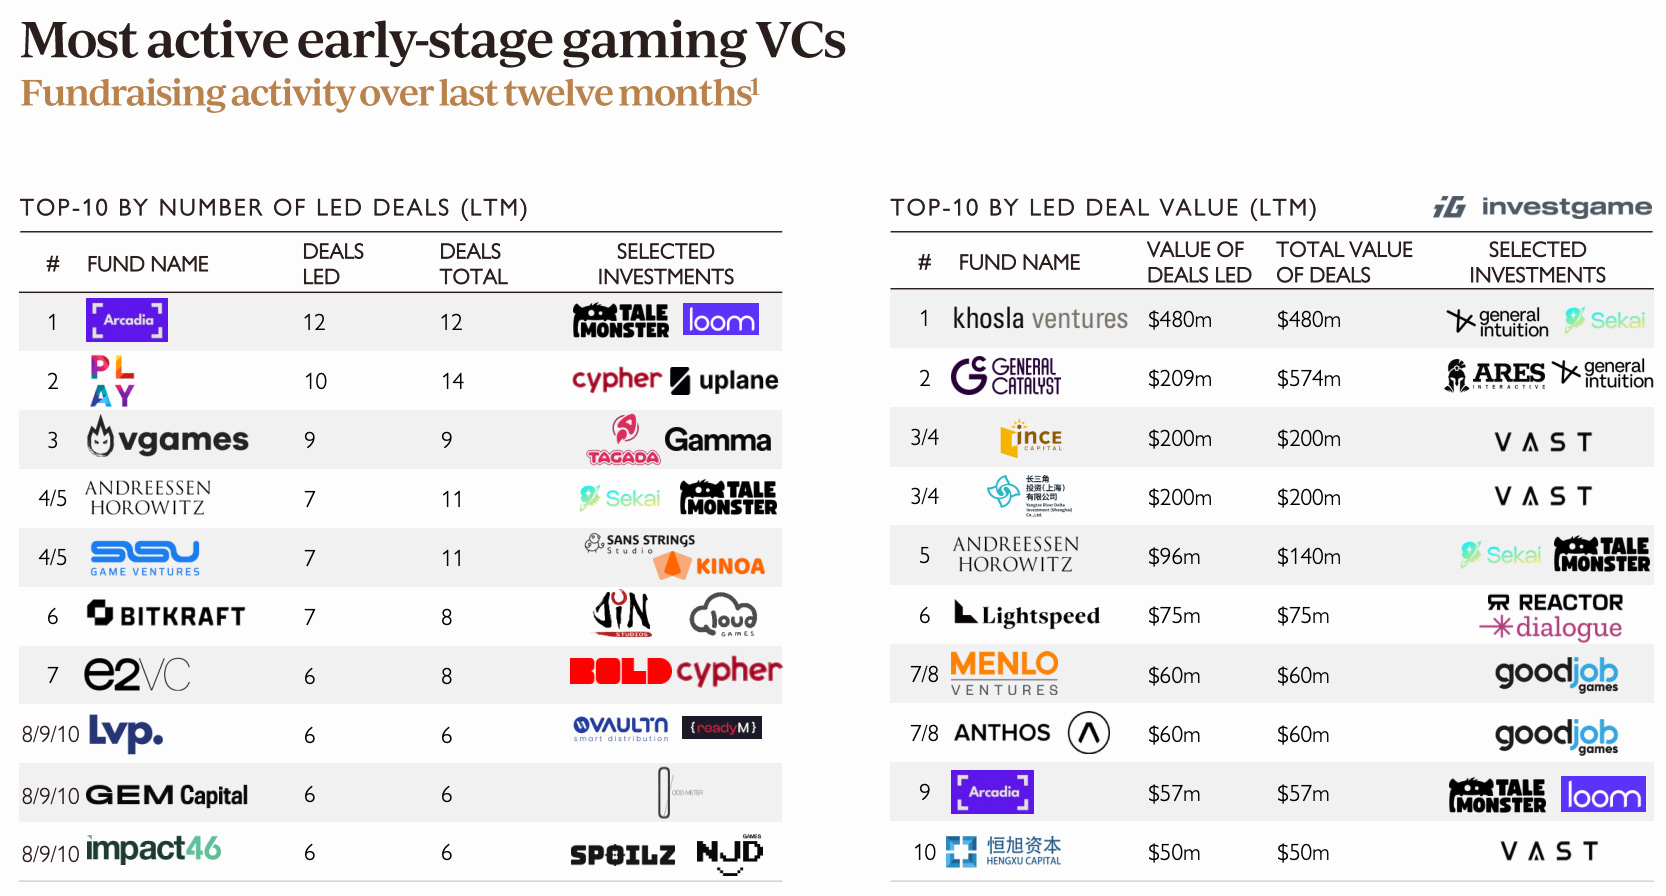
Arcadia, Play Ventures, and vgames were the most active funds over the last 12 months by number of rounds led. By capital invested, the leaders were Khosla Ventures ($480M), General Catalyst ($574M), and Ince Capital ($200M).