

Newzoo’s market revenue represents consumer spending on gaming software and services, including full-game purchases, in-game spending, and console subscription services. It excludes taxes, second-hand trade, advertising, hardware, peripherals, B2B services, and gambling.
The market
According to the current forecast, the gaming market will grow to $213.9 billion in 2026 (+6.1% YoY). All three platforms and every major region are growing.
❗️Newzoo’s final estimate puts the 2025 market at $201.6 billion, above its September 2025 forecast of $188.8 billion. Newzoo attributes the difference primarily to stronger-than-expected PC performance and mobile revenues, including D2C, mini-game, and Tencent revenues.
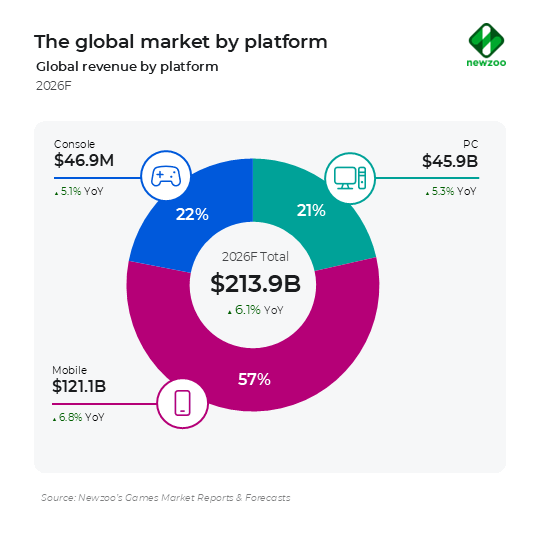
Mobile games remain the industry's largest segment. In 2026, they should earn $121.1 billion (+6.8% YoY). For the first time in a long while, mobile revenue leads the growth. Key drivers include deeper monetization of existing players, Chinese publishers expanding abroad, and the development of D2C channels. Downloads, meanwhile, keep declining.

Managing a distributed dev team shouldn’t mean managing a compliance headache. Mellow’s Contractor Management gives you ready-made contracts, IP compliance, and automated payouts for contractors in 150+ countries — for $35/month per contractor.
❗️According to Sensor Tower’s recent H1’26 report, mobile IAP revenue fell 2.0% YoY (to $40 billion), and downloads dropped 11.9%. But Sensor Tower does not count D2C, third-party stores, or Android revenue in China: exactly the channels Newzoo expects the growth to come from.
Console segment revenue, per Newzoo’s expectations, will be $46.9 billion (+5.1% YoY). The main driver is the November release of Grand Theft Auto VI, which should lift full-game sales revenue by 17.5%. That said, if the game is delayed, there will be no growth, and the segment will most likely close the year down.
The PC market will grow to $45.9 billion (+5.3% YoY). For comparison, the PC segment grew 12% in 2025: the highest annual rate in Newzoo’s entire history of observations. Microtransactions are expected to gain share in the revenue mix. Analysts expect China to drive most PC growth.
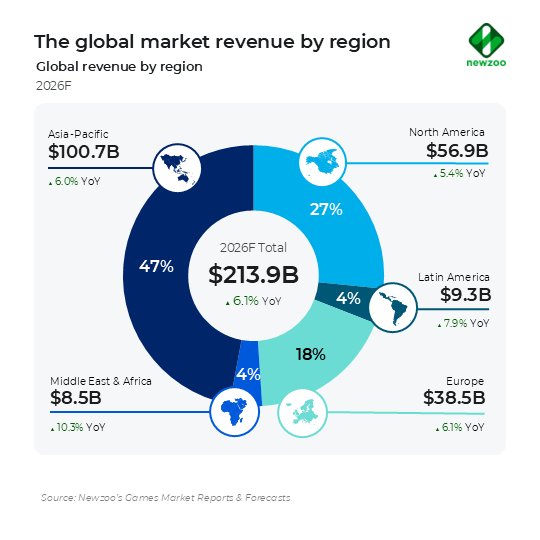
Asia-Pacific, per the forecast, will account for $100.7 billion in revenue (+6% YoY), or 47% of the entire market. North America’s revenue will be $56.9 billion (+5.4% YoY), and Europe’s $38.5 billion (+6.1% YoY).
The Middle East and Africa are growing fastest, at $8.5 billion (+10.3% YoY). Latin America will grow 7.9% in 2026, with the region’s revenue reaching $9.3 billion. Together, though, these two regions account for only 8% of the global market.
China and the US will account for 52% of all consumer spending on games in 2026.
Players
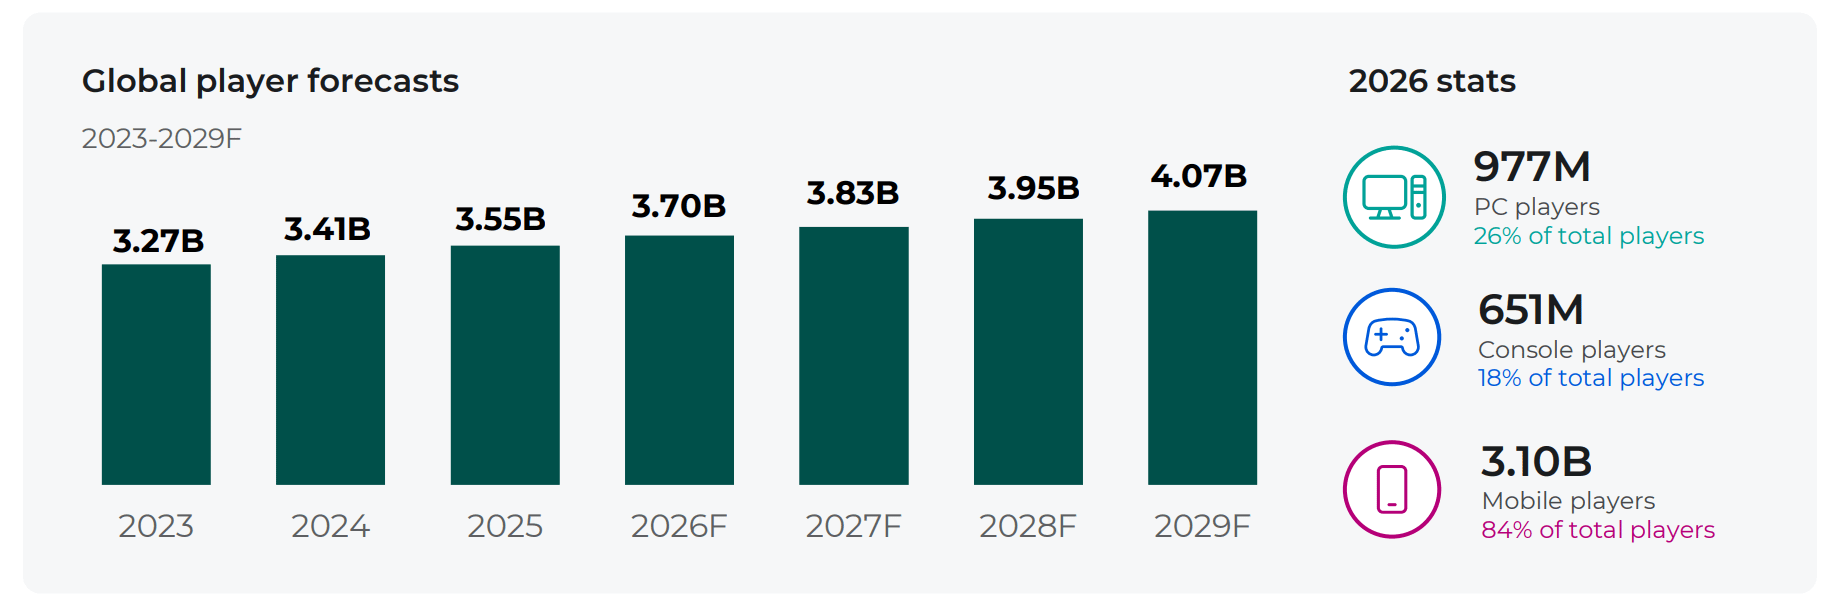
In 2026, there should be 3.7 billion players worldwide (+4.4% YoY). By 2029, that number should grow to 4.07 billion, at a 3.2% compound annual growth rate.
3.1 billion people play mobile games, which is 84% of all players. 977 million people play on PC (26%), and 651 million on consoles (18%).
Game penetration among the online audience will rise from 61.5% to 62.0%. Industry growth largely comes from the growth in internet users: their number will rise to 5.97 billion (+3.5% YoY).
Newzoo notes that market growth from new users is limited. The work will have to happen within the existing audience base.
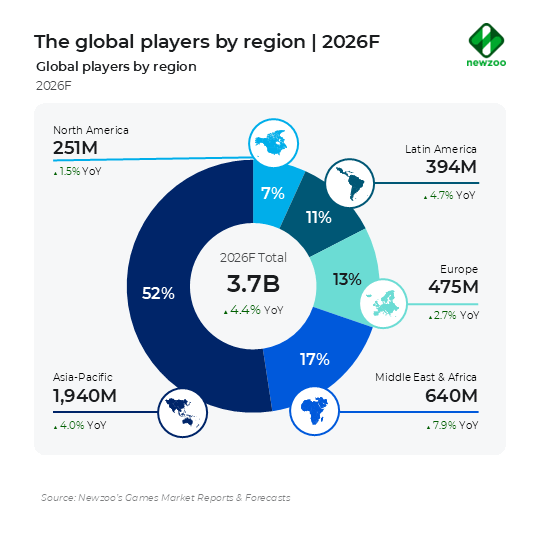
APAC is the largest region by audience (1.94 billion players; +4% YoY). Next are MEA (640 million; +7.9% YoY) and Europe (475 million; +2.7% YoY).
Latin America has 394 million players (+4.7% YoY), and North America has 251 million (+1.5% YoY).
❗️North America grows the slowest of all regions by audience, but the region’s revenue is $56.9 billion: roughly $227 per player per year. In MENA, with 640 million players, it comes out to about $13 per person. The region is growing fast in both money and people, but the gap in absolute numbers is enormous.